Get a fair settlement for your totaled vehicle in Chicago
If your vehicle was declared a total loss in Chicago, Illinois, the insurer's first offer is frequently lower than what it actually costs to replace your car. Local conditions and your Illinois appraisal-clause rights both shape what a fair settlement looks like — here's what Chicago drivers should know.
Chicago at a glance
What leads to totaled vehicles in Chicago
Where you drive shapes how — and how often — a vehicle gets declared a total loss. These Chicago-specific factors come up repeatedly in Illinois total-loss claims, and each one is backed by the independent sources listed at the end of this page:
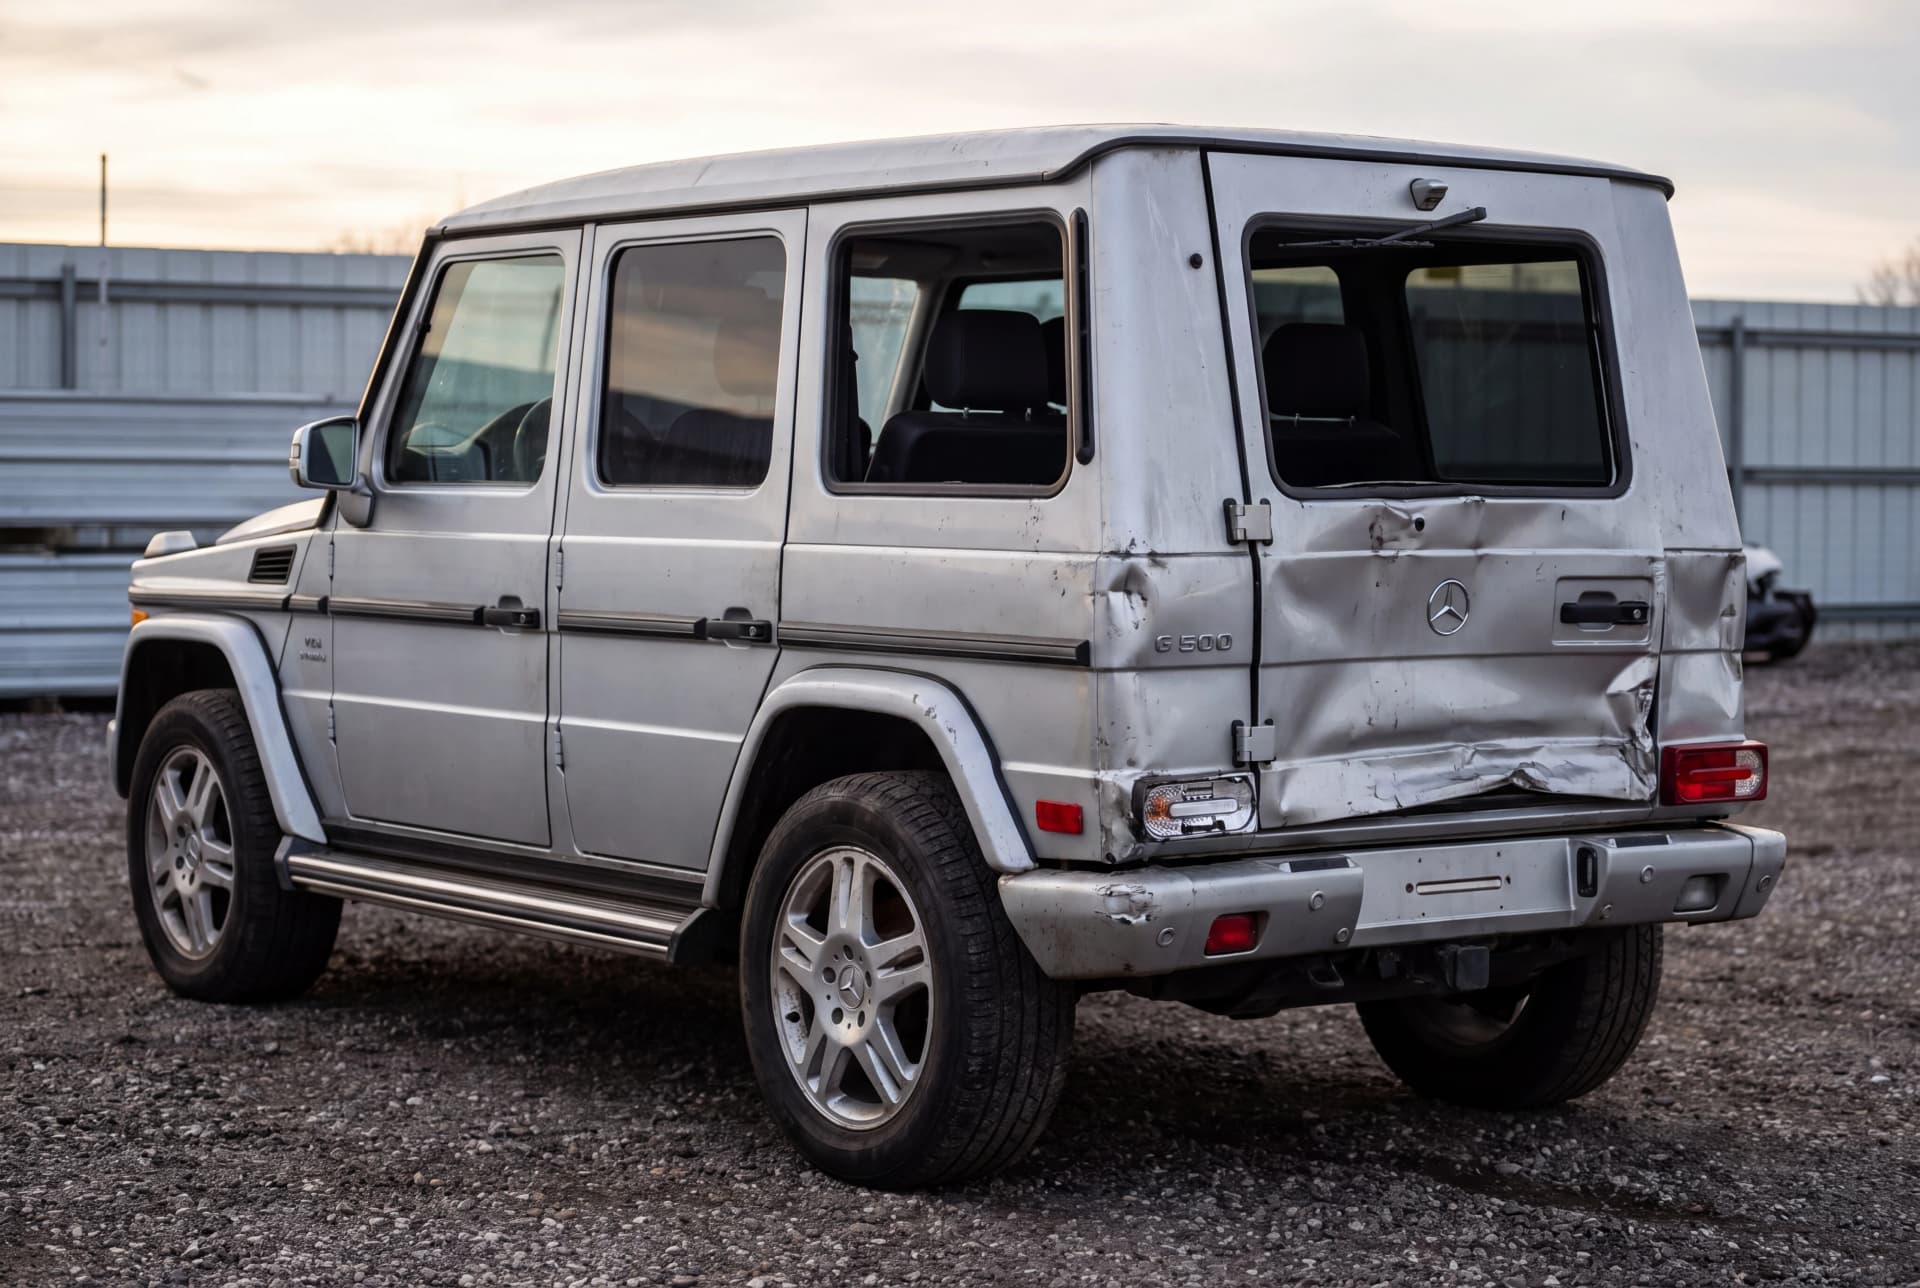
Another successful outcome in Illinois
“I had an excellent experience working with Jonathon at Second Appraisal. I hired him to help with a difficult vehicle valuation dispute after my insurance company’s initial valuation came in well below what I believed the vehicle was worth. I got them up 6k, but that was still short of what I felt was fair.”
When a total loss claim was filed for a 2003 Mercedes-Benz G-Class in Illinois, the insurance company initially offered $29,376. Our research showed that the initial offer was too low, so the dispute went through the policy appraisal clause. The final settlement came to $38,800, which recovered $9,424 above the first offer.
- State Farm’s first offer
- $29,376
- Recovered above the offer
- +$9,424
- Total settlement
- $38,800
One customer's result, before our fee.
Total-loss help in IllinoisHow a total loss works in Illinois
Insurance carriers in Illinois use the Total Loss Formula (TLF) method. When the cost of repair plus the salvage value of your damaged vehicle equals or exceeds its pre-loss actual cash value (ACV), your insurer will declare your vehicle a total loss rather than authorize the repair. From that point, the dispute shifts from "will they fix it?" to "how much will they pay?"
For the full breakdown of your statutory rights, the total-loss formula, and the appraisal-clause playbook, see our Illinois total-loss appraisal guide. New to the process? Start with what to do when your car is totaled.
How SecondAppraisal helps Chicago drivers
- Free appraisal consultation — we confirm your offer is below fair market value before you commit.
- VIN-decoded option audit so every factory feature is credited.
- Accurate, local comparable-vehicle research for the Chicago market.
- Line-by-line audit of the insurer's condition and mileage adjustments.
- Once you invoke the appraisal clause, we carry out the appraisal process for you.
Frequently asked questions
Do I need a local appraiser to dispute a total-loss offer in Chicago?▼
What does an independent total-loss appraisal cost in Chicago?▼
How long does a Chicago total-loss appraisal take?▼
Can I invoke the appraisal clause on a third-party claim in Illinois?▼
Sources
Every Chicago-specific fact above is independently verified against at least two unique sources. Citations below link to the original references.
Chicago recorded a population of 2,746,388 in the 2020 U.S. Census.
- census.gov ↗ — “Population, Census, April 1, 2020 2,746,388”
- wikipedia.org ↗ — “| 2020 | 2,746,388 | 1.9% |”
The Chicago-Naperville-Elgin metro area recorded 36,272 vehicle thefts in 2023, the 3rd-highest total of any U.S. metropolitan area.
- nicb.org ↗ — “3 CBSA Chicago-Naperville-Elgin, IL-IN-WI 2023 Thefts 36,272 % Change 2022 to 2023 9%”
- waautotheftpreventionauthority.org ↗ — “3 | Chicago-Naperville-Elgin, IL-IN-WI | | 36,272 | | | 9%”
Illinois reported 41,528 vehicle thefts in 2023, the 5th-highest total of any U.S. state.
- nicb.org ↗ — “5 State Illinois 2023 Theft 41,528”
- iii.org ↗ — “| 5 | Illinois | 41,528 | 38,649 | 7 |”
Pushing back on a low Chicago total-loss offer?
Start your free appraisal consultation in 5 minutes. We review your offer, audit the insurer's adjustments, and—if you invoke your appraisal clause—run the appraisal process for you.
Get My Free Appraisal Consultation