Get the fair value you deserve for your totaled vehicle in Illinois
In Illinois, your auto policy's appraisal clause gives you the right to appoint SecondAppraisal as your independent appraiser in a total-loss dispute.
Key takeaway
In Illinois, 215 ILCS 5/154.10, which applies to policies issued or renewed on or after July 1, 2025, requires the insurance company, upon the determination of a total loss of an insured vehicle, to provide the insured with a brief description of how that determination was made, including any available repair estimate, estimated vehicle salvage value, assessed market value, and other costs and calculations used. Under the Right of Recourse in 50 Ill. Adm. Code § 919.80(c)(2)(F), if within 30 days after receipt of the claim draft the insured cannot purchase a comparable vehicle in excess of the market value the company determined, the company will reopen its claim file, unless its documentation to the insured at the time of settlement gave written notice of the availability and location of a specified comparable vehicle of the same manufacturer and year, with similar body style and options and in condition as good as or better than the total loss vehicle, identified by its vehicle identification number, that could have been purchased for that market value before applicable deductions.
How SecondAppraisal helps
- •Free appraisal consultation — we review your offer before you commit.
- •At least $1,000 more, or your fee is waived. This applies once we accept your consultation and serve as your appraiser. The starting point is your insurer's offer on the day we accept. If the appraisal award, or a higher offer your insurer makes instead, is less than $1,000 above it, we waive our $495 Appointed Appraiser Service fee. If an umpire is needed, the umpire's fee is separate.
- •Average increase: $3,648 over the insurer's first offer (264 finished consultations that settled at or above the first offer, through Sep 25, 2026, before our fee).
How a total loss works in Illinois
Insurance carriers in Illinois use the Total Loss Formula (TLF) method. When the cost of repair plus the salvage value of your damaged vehicle equals or exceeds its pre-loss actual cash value (ACV), your insurer will declare your vehicle a total loss rather than authorize the repair. From that point, the dispute shifts from "will they fix it?" to "how much will they pay?"
Your appraisal-clause rights in Illinois
Most US auto policies — including those issued in Illinois — contain an appraisal clause that lets either you or the insurer demand a binding independent appraisal when you disagree on value. When invoked, you and the insurer each select a competent independent appraiser, and typically those two appraisers will agree to a new actual cash value. In the event those two appraisers are unable to agree on a value, the two appraisers can select an Umpire to break ties. Typically, you will split the cost of the third appraiser/umpire with the insurance carrier 50/50. In the event that the two appraisers are unable to agree on an umpire, the insured or the insurance carrier can petition a court with jurisdiction to select one. This rarely happens, but the chance isn't zero. The resulting valuation from any two appraisers and/or the umpire is binding.
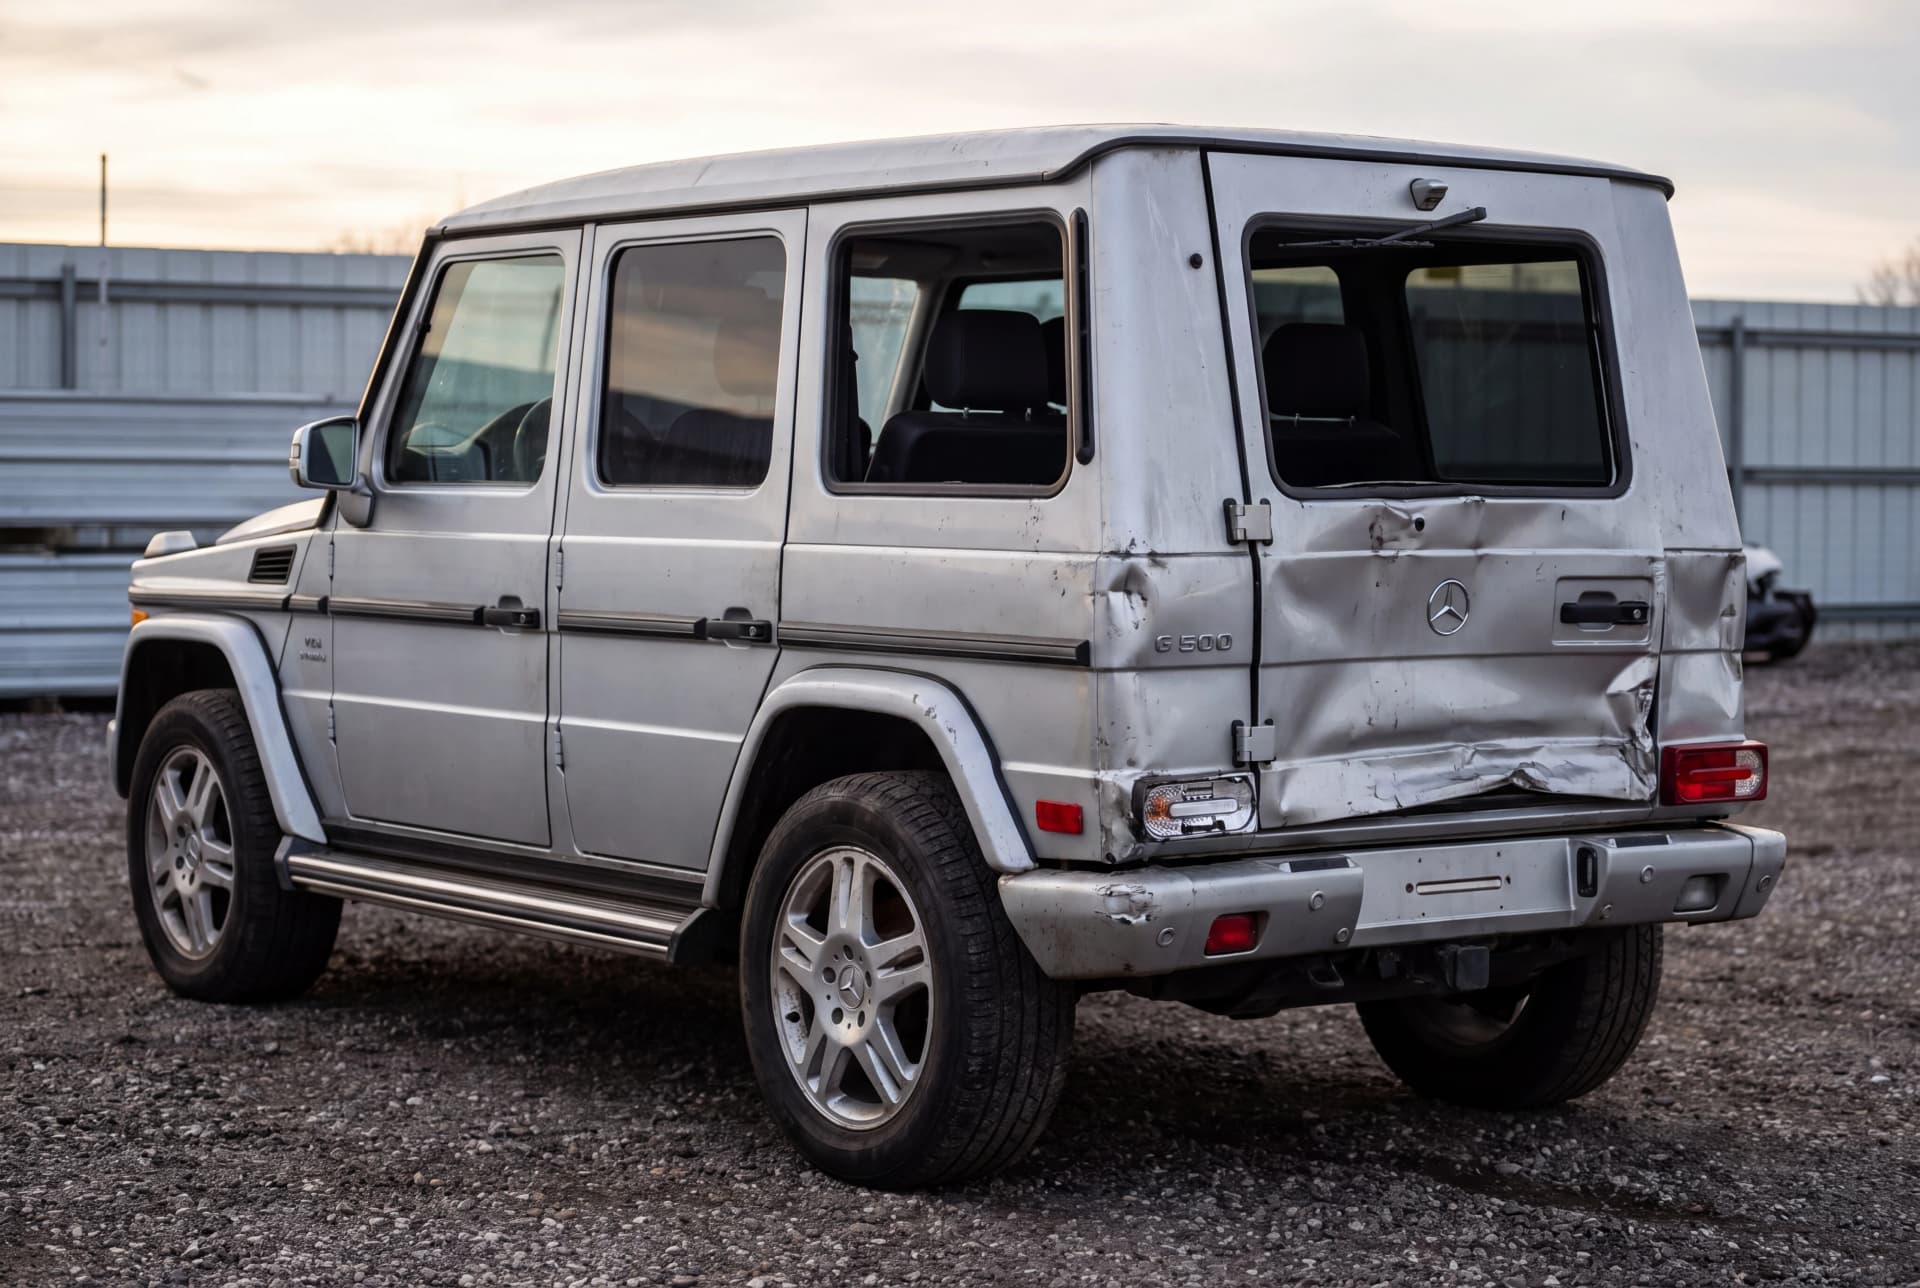
Another successful outcome in Illinois
“I had an excellent experience working with Jonathon at Second Appraisal. I hired him to help with a difficult vehicle valuation dispute after my insurance company’s initial valuation came in well below what I believed the vehicle was worth. I got them up 6k, but that was still short of what I felt was fair.”
When a total loss claim was filed for a 2003 Mercedes-Benz G-Class in Illinois, the insurance company initially offered $29,376. Our research showed that the initial offer was too low, so the dispute went through the policy appraisal clause. The final settlement came to $38,800, which recovered $9,424 above the first offer.
- State Farm’s first offer
- $29,376
- Recovered above the offer
- +$9,424
- Total settlement
- $38,800
One customer's result, before our fee.
Total-loss help in IllinoisYour Illinois rights at a glance
Description of the total-loss determination under 215 ILCS 5/154.10
For policies issued or renewed on or after July 1, 2025, 215 ILCS 5/154.10 requires the insurer, on determination of a total loss, to provide the insured with a brief description of how that determination was made — including any available repair estimate, estimated salvage value, assessed market value, and other costs and calculations used. That gives you statutory leverage to demand the underlying math behind the total-loss declaration.
30-day Right of Recourse under 50 Ill. Adm. Code § 919.80(c)(2)(F)
If, within 30 days after receipt of the claim draft, the insured cannot purchase a comparable vehicle in excess of the offered market value, the insurer must reopen its claim file and either (i) locate a comparable vehicle, (ii) pay the difference, (iii) offer a replacement under § 919.80(c)(1), or (iv) conclude the settlement under the appraisal section of the contract, which is binding against both parties without waiving any other rights.
Sales tax, title, and transfer fees under 215 ILCS 5/154.9
For policies issued or renewed on or after July 1, 2022, 215 ILCS 5/154.9 requires the insurer to pay any state or local use/occupation tax and title/transfer fees on the replacement vehicle, or to reimburse those amounts on a cash settlement when the insured purchases or leases a replacement within 30 days and substantiates the purchase within 33 days. Leased-vehicle taxes are deemed incurred at lease inception.
Illinois Total Loss Framework — 215 ILCS 5/154.5–154.10 + 50 IAC § 919.80
50 Ill. Adm. Code § 919.80(c) sets a closed list of valuation methodologies (printed source published at least every 2 months covering 5 model years, electronic source covering 85% of makes/models for the last 15 years built on at least 1.5 million vehicles with metropolitan-area data, electronic comparable service requiring 2 vehicles from licensed Illinois dealers within 50 miles, or 2 written dealer quotes). The "Right of Recourse" at § 919.80(c)(2)(F) is the operational engine: if the insured cannot purchase a comparable vehicle for the offered amount within 30 days, the insurer must reopen the file and either locate a comparable, pay the difference, offer a replacement, or move to the appraisal clause. 215 ILCS 5/154.10 (effective July 1, 2025) requires the insurer to give the insured a brief description of how the total-loss determination was made — repair estimate, salvage value, assessed market value, and the calculations used. Combined with 215 ILCS 5/154.6's improper-claim-practices list and 215 ILCS 5/154.9's sales-tax/title-fee mandate, Illinois law gives policyholders unusually strong documentary leverage.
Illinois Department of Insurance
If you believe your insurer is acting in bad faith, you can file a complaint with Illinois Department of Insurance — Consumer Assistance at 866-445-5364 — idoi.illinois.gov ↗.
Relevant Illinois precedent
How SecondAppraisal helps Illinois policyholders
- Free appraisal consultation — confirm your offer is below fair market value before you commit.
- VIN-decoded option audit so every factory feature is credited.
- Accurate and appropriate comparable vehicle research.
- Line-by-line audit of the insurer's adjustments.
- Once you invoke the appraisal clause, we carry out the appraisal process.
Total-loss help in major Illinois cities
City-specific total-loss guides with local risk factors and your appraisal-clause rights:
Frequently asked questions
What is the total-loss threshold in Illinois?▼
Can I invoke the appraisal clause in a third-party insurance carrier / at-fault insurance carrier claim in Illinois?▼
What does SecondAppraisal cost in Illinois?▼
How long does an Illinois total-loss appraisal take?▼
Ready to push back on a low Illinois total-loss offer?
Start your free appraisal consultation in 5 minutes. At least $1,000 more than your insurer's offer, or your $495 fee is waived, once we accept your consultation. Our results: $3,648 more than the insurer's first offer, on average, before our fee. From 264 finished consultations that settled at or above the insurer's first offer, through September 25, 2026; past results, not a promise.
Get My Free Appraisal Consultation