Get the fair value you deserve for your totaled vehicle in Indiana
In Indiana, your auto policy's appraisal clause gives you the right to appoint SecondAppraisal as your independent appraiser in a total-loss dispute.
How SecondAppraisal helps
- •Free appraisal consultation — we review your offer before you commit.
- •At least $1,000 more, or your fee is waived. This applies once we accept your consultation and serve as your appraiser. The starting point is your insurer's offer on the day we accept. If the appraisal award, or a higher offer your insurer makes instead, is less than $1,000 above it, we waive our $495 Appointed Appraiser Service fee. If an umpire is needed, the umpire's fee is separate.
- •Average increase: $3,648 over the insurer's first offer (264 finished consultations that settled at or above the first offer, through Sep 25, 2026, before our fee).
How a total loss works in Indiana
Insurance carriers in Indiana use the Total Loss Threshold (TLT) method. When the cost to repair your vehicle reaches 70% of its pre-loss actual cash value (ACV), your insurer will declare your vehicle a total loss rather than authorize the repair. From that point, the dispute shifts from "will they fix it?" to "how much will they pay?"
Your appraisal-clause rights in Indiana
Most US auto policies — including those issued in Indiana — contain an appraisal clause that lets either you or the insurer demand a binding independent appraisal when you disagree on value. When invoked, you and the insurer each select a competent independent appraiser, and typically those two appraisers will agree to a new actual cash value. In the event those two appraisers are unable to agree on a value, the two appraisers can select an Umpire to break ties. Typically, you will split the cost of the third appraiser/umpire with the insurance carrier 50/50. In the event that the two appraisers are unable to agree on an umpire, the insured or the insurance carrier can petition a court with jurisdiction to select one. This rarely happens, but the chance isn't zero. The resulting valuation from any two appraisers and/or the umpire is binding.
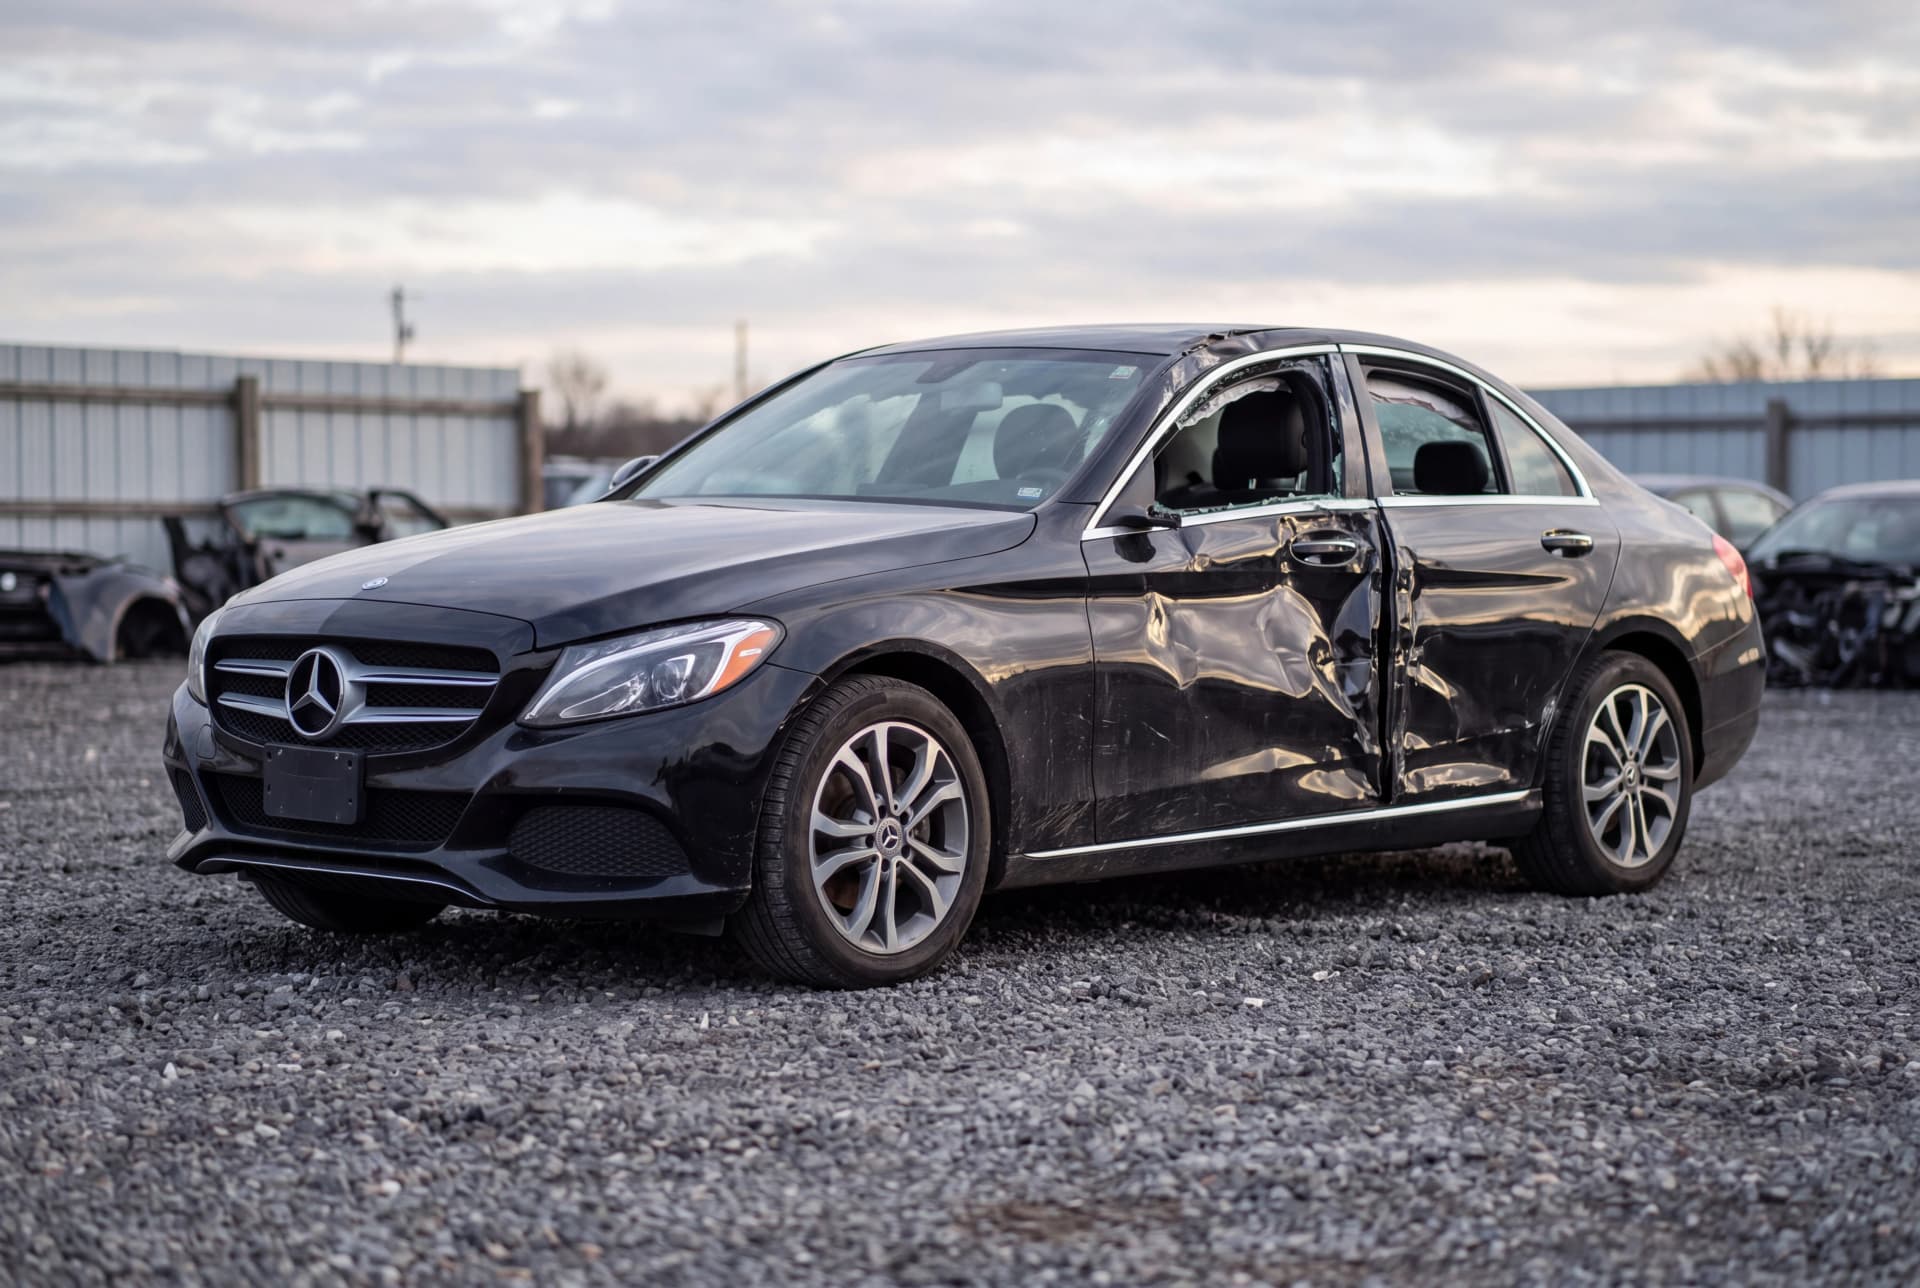
Another successful outcome in Indiana
“A+++++ Second appraiser got a great settlement for me and it was done much quicker than I imaged it would. Jonathan did not give up and followed through with everything Liberty Mutual was denying. I would recommend them over and over.”
When Lynda received a first offer of $10,858 for her 2016 Mercedes-Benz C-Class in Indiana, our research showed that amount was too low. The insurance claim went through the policy's appraisal clause after the insurer brought in its own appraiser. The final settlement came to $13,000, recovering $2,142 above the first offer.
- Liberty Mutual’s first offer
- $10,858
- Recovered above the offer
- +$2,142
- Total settlement
- $13,000
One customer's result, before our fee.
Total-loss help in IndianaIndiana Total Loss Framework — Ind. Code § 27-4-1-4.5 + Erie v. Hickman + Ind. Code § 9-22-3-3
Indiana's total-loss framework rests on two legs plus a contractual mechanism: the UCSPA at Ind. Code § 27-4-1-4.5 (no private right of action; enforced by the Indiana Department of Insurance, with subsection (6)'s prompt-fair-equitable-settlement duty the provision most engaged by a low total-loss offer), and the Erie v. Hickman first-party bad-faith tort, which is the operational lever for policyholders (punitive damages available on clear and convincing evidence under Ind. Code § 34-51-3-2). Ind. Code § 27-4-1-4.5 prescribes no valuation method, so a disputed actual cash value is resolved through the policy's appraisal clause. Ind. Code § 9-22-3-3 requires a salvage title when an insurer has determined that repair is economically impractical; its 70% repair-cost test applies to self-insured businesses and to owners who acquired the vehicle after the damage.
How SecondAppraisal helps Indiana policyholders
- Free appraisal consultation — confirm your offer is below fair market value before you commit.
- VIN-decoded option audit so every factory feature is credited.
- Accurate and appropriate comparable vehicle research.
- Line-by-line audit of the insurer's adjustments.
- Once you invoke the appraisal clause, we carry out the appraisal process.
Total-loss help in major Indiana cities
City-specific total-loss guides with local risk factors and your appraisal-clause rights:
Frequently asked questions
What is the total-loss threshold in Indiana?▼
Can I invoke the appraisal clause in a third-party insurance carrier / at-fault insurance carrier claim in Indiana?▼
What does SecondAppraisal cost in Indiana?▼
How long does an Indiana total-loss appraisal take?▼
Ready to push back on a low Indiana total-loss offer?
Start your free appraisal consultation in 5 minutes. At least $1,000 more than your insurer's offer, or your $495 fee is waived, once we accept your consultation. Our results: $3,648 more than the insurer's first offer, on average, before our fee. From 264 finished consultations that settled at or above the insurer's first offer, through September 25, 2026; past results, not a promise.
Get My Free Appraisal Consultation