Get the fair value you deserve for your totaled vehicle in Louisiana
Your policy's appraisal clause lets you retain a competent, independent appraiser for a total-loss valuation dispute in Louisiana.
Key takeaway
La. R.S. 22:1892(B)(1)(a) applies when an insurer's failure to pay an insured's auto claim within 30 days after receiving satisfactory written proofs of loss and a demand is found "arbitrary, capricious, or without probable cause." The insurer is then subject, in addition to the loss, to a penalty of 50% of the amount found due plus any proven economic damages from the breach, or $1,000, whichever is greater, and to reasonable attorney fees and costs. After a partial payment or tender, the penalty is instead 50% of the difference between that amount and the amount found due, plus those damages. If a policy provides for settling first-party vehicle total losses at actual cash value or by like kind and quality replacement, and the insurer elects a cash settlement based on the actual cost of a comparable vehicle, § 22:1892(B)(5) requires one of three methods for deriving that cost. One is the retail cost from a generally recognized used-vehicle industry source, such as an electronic database, if its valuation documents are provided to the first-party claimant, or a guidebook available to the general public. If the insured demonstrates, with two independent appraisals based on measurable and discernable factors including the vehicle's preloss condition, a higher local-market cash value than the database or guidebook shows, the local market value must be used to determine actual cash value.
How SecondAppraisal helps
- •Free appraisal consultation — we review your offer before you commit.
- •At least $1,000 more, or your fee is waived. This applies once we accept your consultation and serve as your appraiser. The starting point is your insurer's offer on the day we accept. If the appraisal award, or a higher offer your insurer makes instead, is less than $1,000 above it, we waive our $495 Appointed Appraiser Service fee. If an umpire is needed, the umpire's fee is separate.
- •Average increase: $3,648 over the insurer's first offer (264 finished consultations that settled at or above the first offer, through Sep 25, 2026, before our fee).
How a total loss works in Louisiana
Insurance carriers in Louisiana use the Total Loss Threshold (TLT) method. When the cost to repair your vehicle reaches 75% of its pre-loss actual cash value (ACV), your insurer will declare your vehicle a total loss rather than authorize the repair. From that point, the dispute shifts from "will they fix it?" to "how much will they pay?"
Your appraisal-clause rights in Louisiana
Most US auto policies — including those issued in Louisiana — contain an appraisal clause that lets either you or the insurer demand a binding independent appraisal when you disagree on value. When invoked, you and the insurer each select a competent independent appraiser, and typically those two appraisers will agree to a new actual cash value. In the event those two appraisers are unable to agree on a value, the two appraisers can select an Umpire to break ties. Typically, you will split the cost of the third appraiser/umpire with the insurance carrier 50/50. In the event that the two appraisers are unable to agree on an umpire, the insured or the insurance carrier can petition a court with jurisdiction to select one. This rarely happens, but the chance isn't zero. The resulting valuation from any two appraisers and/or the umpire is binding.
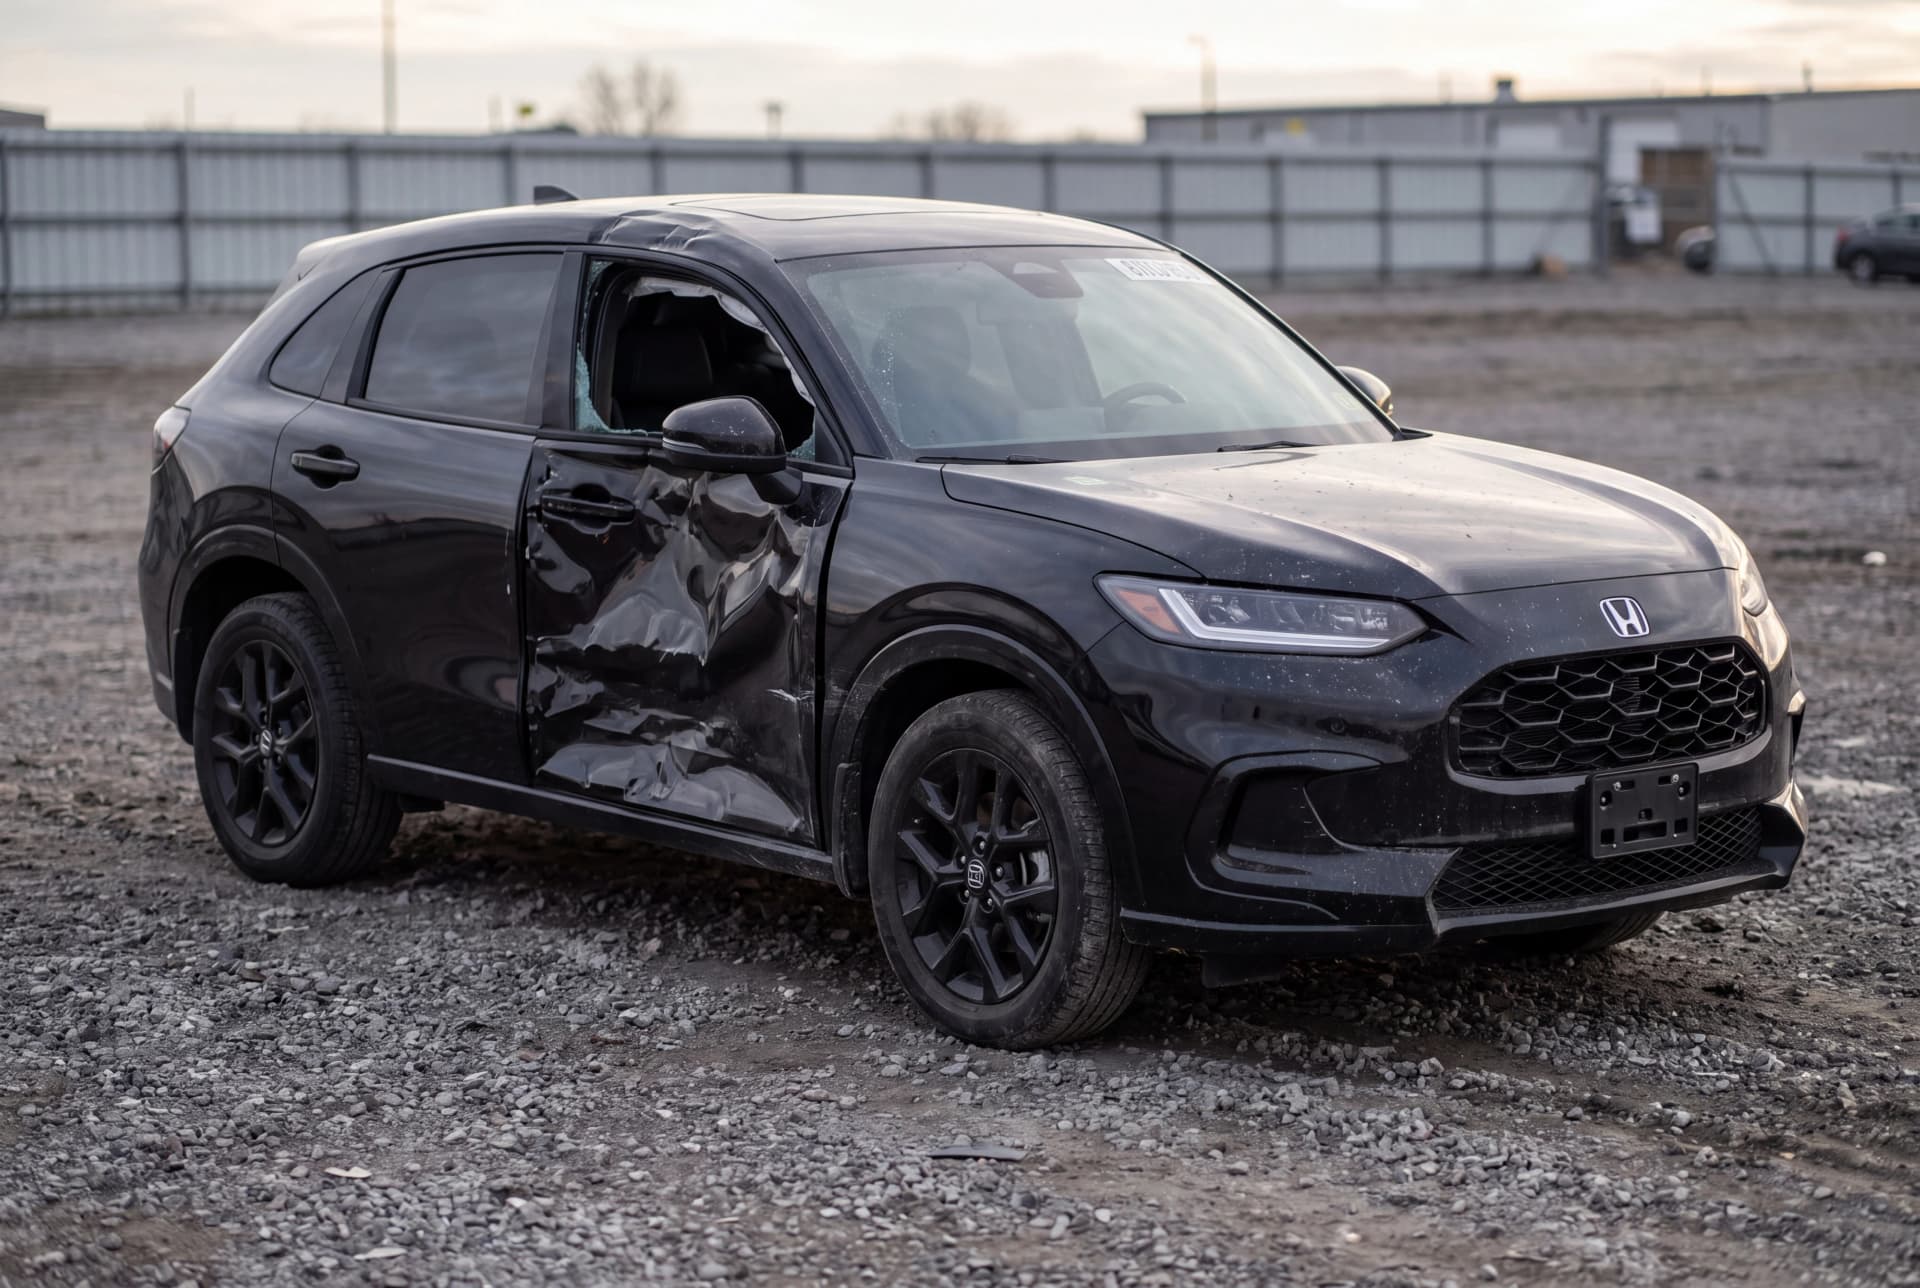
Another successful outcome in Louisiana
“Jonathan with Second Appraisal was phenomenal. He truly superseded my expectations. I had pre-authorized my payment on 6/29/2026, by 7/07/2026 everything was complete. I received an additional $5,360.00 for my totaled vehicle. I'm grateful that this situation is now complete. Thanks a bunch for your assistance”
When Kendra was offered $18,440 for her 2024 Honda HR-V in Louisiana, our research showed the initial offer was too low. The matter was resolved through the policy appraisal clause after the insurer brought in its own appraiser. The final settlement came to $23,800, securing $5,360 more than the insurer first offered.
- State Farm’s first offer
- $18,440
- Recovered above the offer
- +$5,360
- Total settlement
- $23,800
One customer's result, before our fee.
Total-loss help in LouisianaYour Louisiana rights at a glance
50% penalty + attorney's fees under La. R.S. 22:1892
If the insurer fails to pay the claim within 30 days after receipt of satisfactory proof of loss and the failure is arbitrary, capricious, or without probable cause, the insured is entitled to recover the amount of the loss plus a penalty of 50% of the amount found due plus reasonable attorney's fees.
Statutory total-loss valuation methods + two-appraisal override under La. R.S. 22:1892(B)(5)
Louisiana's total-loss valuation methodology is set by statute. La. R.S. 22:1892(B)(5) requires a cash settlement for a comparable vehicle to be derived from one of: (a) a fair market value survey of qualified retail dealers in the local market area; (b) a recognized used-vehicle industry source (an electronic database, with the valuation documents provided to the claimant, or a publicly available guidebook); or (c) a qualified expert appraiser selected and agreed upon by the insured and insurer. Critically, under (b) the insured may force use of the local-market value by presenting two independent appraisals based on measurable and discernable factors, including the vehicle's preloss condition.
Louisiana Revised Statutes Title 22 § 1892 — Claims Practices
La. R.S. 22:1892 imposes a 30-day prompt-payment requirement and, on a finding that the insurer's failure to pay was "arbitrary, capricious, or without probable cause," adds a penalty of 50% of the amount due plus reasonable attorney's fees. La. R.S. 22:1973 was repealed by Act 3 of 2024, effective July 1, 2024. Below the bad-faith statutes, the total-loss valuation methodology is set by statute at La. R.S. 22:1892(B)(5) — a dealer fair-market-value survey, a recognized used-vehicle database/guidebook (which the insured may rebut with two independent appraisals showing a higher local-market value), or a mutually agreed qualified expert appraiser — and the 75% repair-to-market-value salvage threshold lives at La. R.S. 32:702.
Common things to look for in Louisiana
Recognize these scenarios in your offer letter or comparable report — and what we do about them.
Insurer arguing the failure to pay was "reasonable" because of an honest disagreement over valuation
La. R.S. 22:1892(B)(1)(a) penalizes a failure to pay within thirty days of satisfactory proof of loss when the failure is "arbitrary, capricious, or without probable cause." Document any departure from the statutory methods at La. R.S. 22:1892(B)(5) — for example, standing on a database value the insured has rebutted with two independent appraisals showing a higher local-market value, or drawing a "survey" from dealers outside the local market area when there are dealers in it (§ 22:1892(B)(5)(a) allows the nearest reasonable market only when the local market area has none).
Standing on a low database value the insured has rebutted with appraisals
Under La. R.S. 22:1892(B)(5)(b), once the insured presents two independent appraisals — based on measurable and discernable factors including the vehicle's preloss condition — showing a higher local-market value than the database or guidebook figure, the statute requires the local-market value to be used. An insurer that ignores qualifying appraisals and stands on the database number departs from the statute; document it for a § 22:1892 "arbitrary, capricious, or without probable cause" claim.
Louisiana Department of Insurance
If you believe your insurer is acting in bad faith, you can file a complaint with Louisiana Department of Insurance — Office of Consumer Services at 800-259-5300 — ldi.la.gov ↗.
Relevant Louisiana precedent
How SecondAppraisal helps Louisiana policyholders
- Free appraisal consultation — confirm your offer is below fair market value before you commit.
- VIN-decoded option audit so every factory feature is credited.
- Accurate and appropriate comparable vehicle research.
- Line-by-line audit of the insurer's adjustments.
- Once you invoke the appraisal clause, we carry out the appraisal process.
Frequently asked questions
What is the total-loss threshold in Louisiana?▼
Can I invoke the appraisal clause in a third-party insurance carrier / at-fault insurance carrier claim in Louisiana?▼
What does SecondAppraisal cost in Louisiana?▼
How long does a Louisiana total-loss appraisal take?▼
Ready to push back on a low Louisiana total-loss offer?
Start your free appraisal consultation in 5 minutes. At least $1,000 more than your insurer's offer, or your $495 fee is waived, once we accept your consultation. Our results: $3,648 more than the insurer's first offer, on average, before our fee. From 264 finished consultations that settled at or above the insurer's first offer, through September 25, 2026; past results, not a promise.
Get My Free Appraisal Consultation