Get the fair value you deserve for your totaled vehicle in Missouri
In Missouri, your auto policy's appraisal clause gives you the right to appoint SecondAppraisal as your independent appraiser in a total-loss dispute.
Key takeaway
Missouri's hammer is Mo. Rev. Stat. § 375.420 — the vexatious-refusal-to-pay statute. When an insurer refuses to pay a property-damage claim without reasonable cause or excuse, the court can award up to 20% of the first $1,500 of loss plus 10% of the excess plus reasonable attorney's fees on top of the contract amount and interest. 20 CSR 100-1.050 supplies the general claim-handling discipline (betterment/depreciation itemization, repair-to-pre-loss duty, timing rules), though Missouri has not adopted the NAIC closed-list valuation or right-of-recourse provisions some other states have.
How SecondAppraisal helps
- •Free appraisal consultation — we review your offer before you commit.
- •At least $1,000 more, or your fee is waived. This applies once we accept your consultation and serve as your appraiser. The starting point is your insurer's offer on the day we accept. If the appraisal award, or a higher offer your insurer makes instead, is less than $1,000 above it, we waive our $495 Appointed Appraiser Service fee. If an umpire is needed, the umpire's fee is separate.
- •Average increase: $3,648 over the insurer's first offer (264 finished consultations that settled at or above the first offer, through Sep 25, 2026, before our fee).
How a total loss works in Missouri
Insurance carriers in Missouri use the Total Loss Threshold (TLT) method. When the cost to repair your vehicle reaches 80% of its pre-loss actual cash value (ACV), your insurer will declare your vehicle a total loss rather than authorize the repair. From that point, the dispute shifts from "will they fix it?" to "how much will they pay?"
Your appraisal-clause rights in Missouri
Most US auto policies — including those issued in Missouri — contain an appraisal clause that lets either you or the insurer demand a binding independent appraisal when you disagree on value. When invoked, you and the insurer each select a competent independent appraiser, and typically those two appraisers will agree to a new actual cash value. In the event those two appraisers are unable to agree on a value, the two appraisers can select an Umpire to break ties. Typically, you will split the cost of the third appraiser/umpire with the insurance carrier 50/50. In the event that the two appraisers are unable to agree on an umpire, the insured or the insurance carrier can petition a court with jurisdiction to select one. This rarely happens, but the chance isn't zero. The resulting valuation from any two appraisers and/or the umpire is binding.
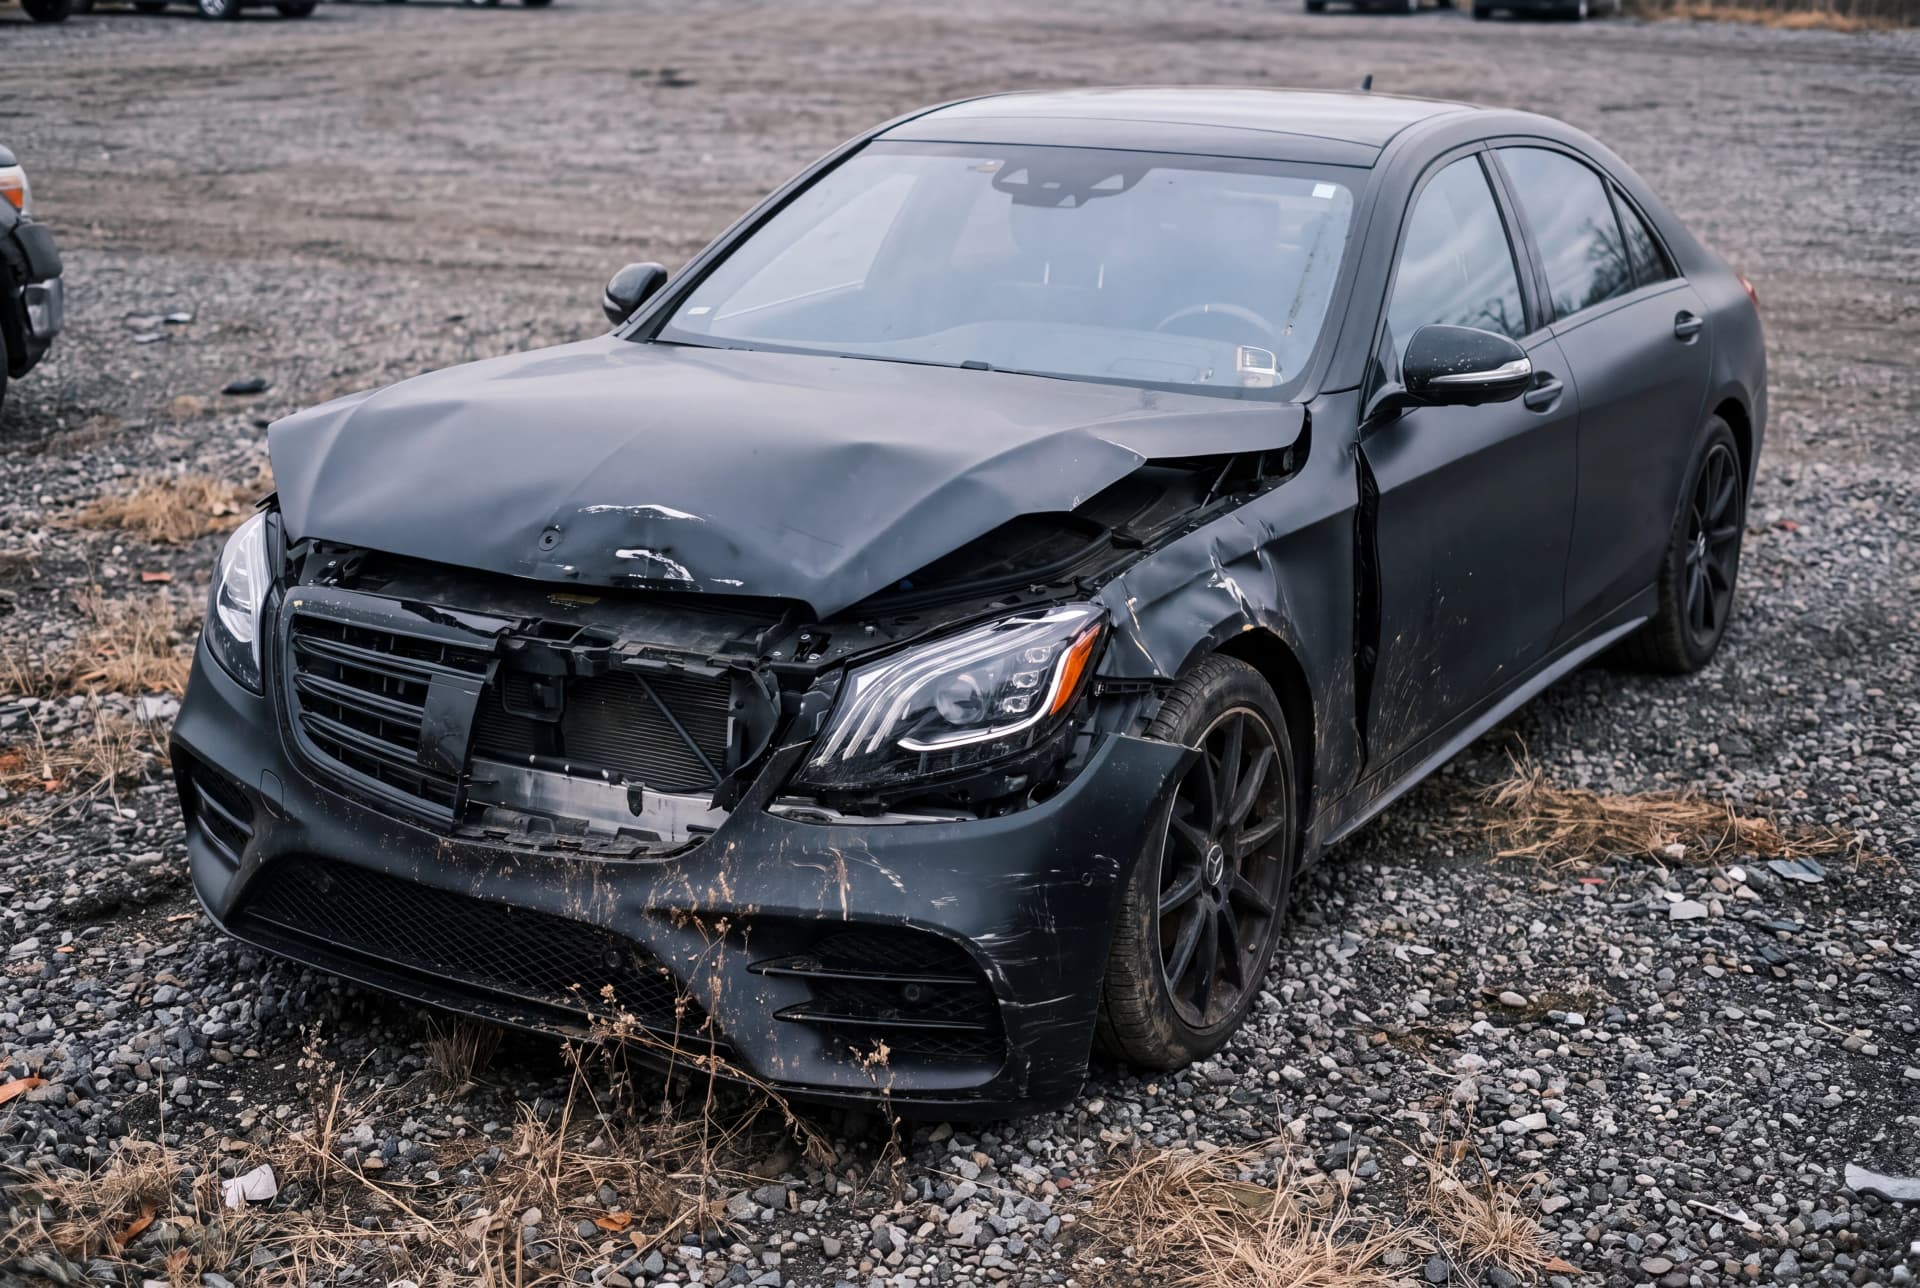
Another successful outcome in Missouri
“Definitely use this guys, you have nothing to lose!”
Jaspreet received an initial offer of $31,941 from the insurance company for the 2019 Mercedes-Benz S-Class. Our research showed that offer was too low, and the matter went through the policy's appraisal clause after the insurer brought in its own appraiser. The final settlement came to $37,000, recovering $5,059 above the first offer.
- State Farm’s first offer
- $31,941
- Recovered above the offer
- +$5,059
- Total settlement
- $37,000
One customer's result, before our fee.
Total-loss help in MissouriYour Missouri rights at a glance
Vexatious-refusal damages and attorney's fees under Mo. Rev. Stat. § 375.420
When an insurer refuses to pay a property-damage claim "without reasonable cause or excuse," the court may award the policyholder, in addition to the contract amount and interest, damages up to 20% of the first $1,500 of loss plus 10% of any excess, plus a reasonable attorney's fee.
20 CSR 100-1.050 general claim-handling discipline
The regulation imposes a 15-working-day acknowledge/deny window, a 30-day investigation-completion timeline for general claims, a repair-to-pre-loss-condition duty, and a betterment/depreciation rule under which reductions "shall be itemized and shall be appropriate in amount." Missouri has not adopted the NAIC closed-list valuation methods, the 30-day right of recourse, or the mandatory sales-tax-on-total-loss provision used in some other states; the genuine regulatory anchors are the timing rules and the betterment/depreciation itemization standard.
80% salvage-vehicle definition under Mo. Rev. Stat. § 301.010(55)
The 80% repair-to-fair-market-value salvage-branding threshold lives in the "Salvage vehicle" definition at § 301.010(55), not at § 301.193. It applies only when the vehicle was damaged within six years of the manufacturer's model-year designation.
Missouri Total Loss Framework — RSMo §§ 375.1007, 375.420 + 20 CSR 100-1.050
Missouri's total-loss framework rests on the UCSPA at Mo. Rev. Stat. § 375.1007 (no private right of action), the general claim-handling regulation at 20 CSR 100-1.050 (which includes a betterment/depreciation rule that such reductions be itemized and appropriate in amount, a repair-to-pre-loss-condition duty, and a 15-working-day acknowledge/deny window — but does NOT codify closed-list valuation methods, a "30-day right of recourse," or a mandatory sales-tax-on-total-loss provision), and Mo. Rev. Stat. § 375.420 — the vexatious-refusal-to-pay statute that lets a successful claimant recover, on top of the contract amount and interest, damages of up to 20% of the first $1,500 of loss plus 10% of the excess and reasonable attorney's fees, when the insurer refused to pay "without reasonable cause or excuse." The 80% salvage-branding threshold lives at § 301.010(55) (the "Salvage vehicle" definition) and applies to vehicles damaged within six years of the manufacturer's model-year designation.
Common things to look for in Missouri
Recognize these scenarios in your offer letter or comparable report — and what we do about them.
Insurer treating the § 375.420 "reasonable cause or excuse" standard as a high bar
An insurer's failure to investigate or its reliance on a position without legal or factual support can support a vexatious-refusal finding. Build your file around documented regulatory deviations and the timeline of the insurer's conduct.
Lump-sum or non-appropriate betterment/depreciation reductions
20 CSR 100-1.050(2)(E) requires betterment/depreciation reductions to be itemized and appropriate in amount. A line-item like "condition adjustment: $1,200" with no itemization or rational basis violates that requirement.
Insurer citing a Missouri "30-day right of recourse" or mandatory total-loss tax-inclusion regulation
Neither provision is codified in 20 CSR 100-1.050. If a carrier or third-party administrator references one, ask for the precise regulatory citation; the genuine framework is the betterment/depreciation itemization rule plus the policy language and proof of replacement-vehicle purchase for sales-tax recovery.
Missouri Department of Insurance
If you believe your insurer is acting in bad faith, you can file a complaint with Missouri Department of Commerce and Insurance — Consumer Affairs at 800-726-7390 — insurance.mo.gov ↗.
Relevant Missouri precedent
How SecondAppraisal helps Missouri policyholders
- Free appraisal consultation — confirm your offer is below fair market value before you commit.
- VIN-decoded option audit so every factory feature is credited.
- Accurate and appropriate comparable vehicle research.
- Line-by-line audit of the insurer's adjustments.
- Once you invoke the appraisal clause, we carry out the appraisal process.
Frequently asked questions
What is the total-loss threshold in Missouri?▼
Can I invoke the appraisal clause in a third-party insurance carrier / at-fault insurance carrier claim in Missouri?▼
What does SecondAppraisal cost in Missouri?▼
How long does a Missouri total-loss appraisal take?▼
Ready to push back on a low Missouri total-loss offer?
Start your free appraisal consultation in 5 minutes. At least $1,000 more than your insurer's offer, or your $495 fee is waived, once we accept your consultation. Our results: $3,648 more than the insurer's first offer, on average, before our fee. From 264 finished consultations that settled at or above the insurer's first offer, through September 25, 2026; past results, not a promise.
Get My Free Appraisal Consultation