Get the fair value you deserve for your totaled vehicle in Wyoming
Your policy's appraisal clause lets you retain a competent, independent appraiser for a total-loss valuation dispute in Wyoming.
Key takeaway
Wyoming's § 26-15-124(c) lets a court that renders judgment for a claimant also award a reasonable attorney's fee and interest at 10% per year when the insurer refused to pay "the full amount of a loss covered by the policy" and the refusal was "unreasonable or without cause."
How SecondAppraisal helps
- •Free appraisal consultation — we review your offer before you commit.
- •$1,000 minimum guarantee — if we take your consultation on and can't deliver at least $1,000 in additional value, you pay nothing.
- •Average increase: ~$3,648 across the appraisals we've negotiated.
How a total loss works in Wyoming
Insurance carriers in Wyoming use the Total Loss Formula (TLF) method. When the cost of repair plus the salvage value of your damaged vehicle equals or exceeds its pre-loss actual cash value (ACV), your insurer will declare your vehicle a total loss rather than authorize the repair. From that point, the dispute shifts from "will they fix it?" to "how much will they pay?"
Your appraisal-clause rights in Wyoming
Most US auto policies — including those issued in Wyoming — contain an appraisal clause that lets either you or the insurer demand a binding independent appraisal when you disagree on value. When invoked, you and the insurer each select a competent independent appraiser, and typically those two appraisers will agree to a new actual cash value. In the event those two appraisers are unable to agree on a value, the two appraisers can select an Umpire to break ties. Typically, you will split the cost of the third appraiser/umpire with the insurance carrier 50/50. In the event that the two appraisers are unable to agree on an umpire, the insured or the insurance carrier can petition a court with jurisdiction to select one. This rarely happens, but the chance isn't zero. The resulting valuation from any two appraisers and/or the umpire is binding.
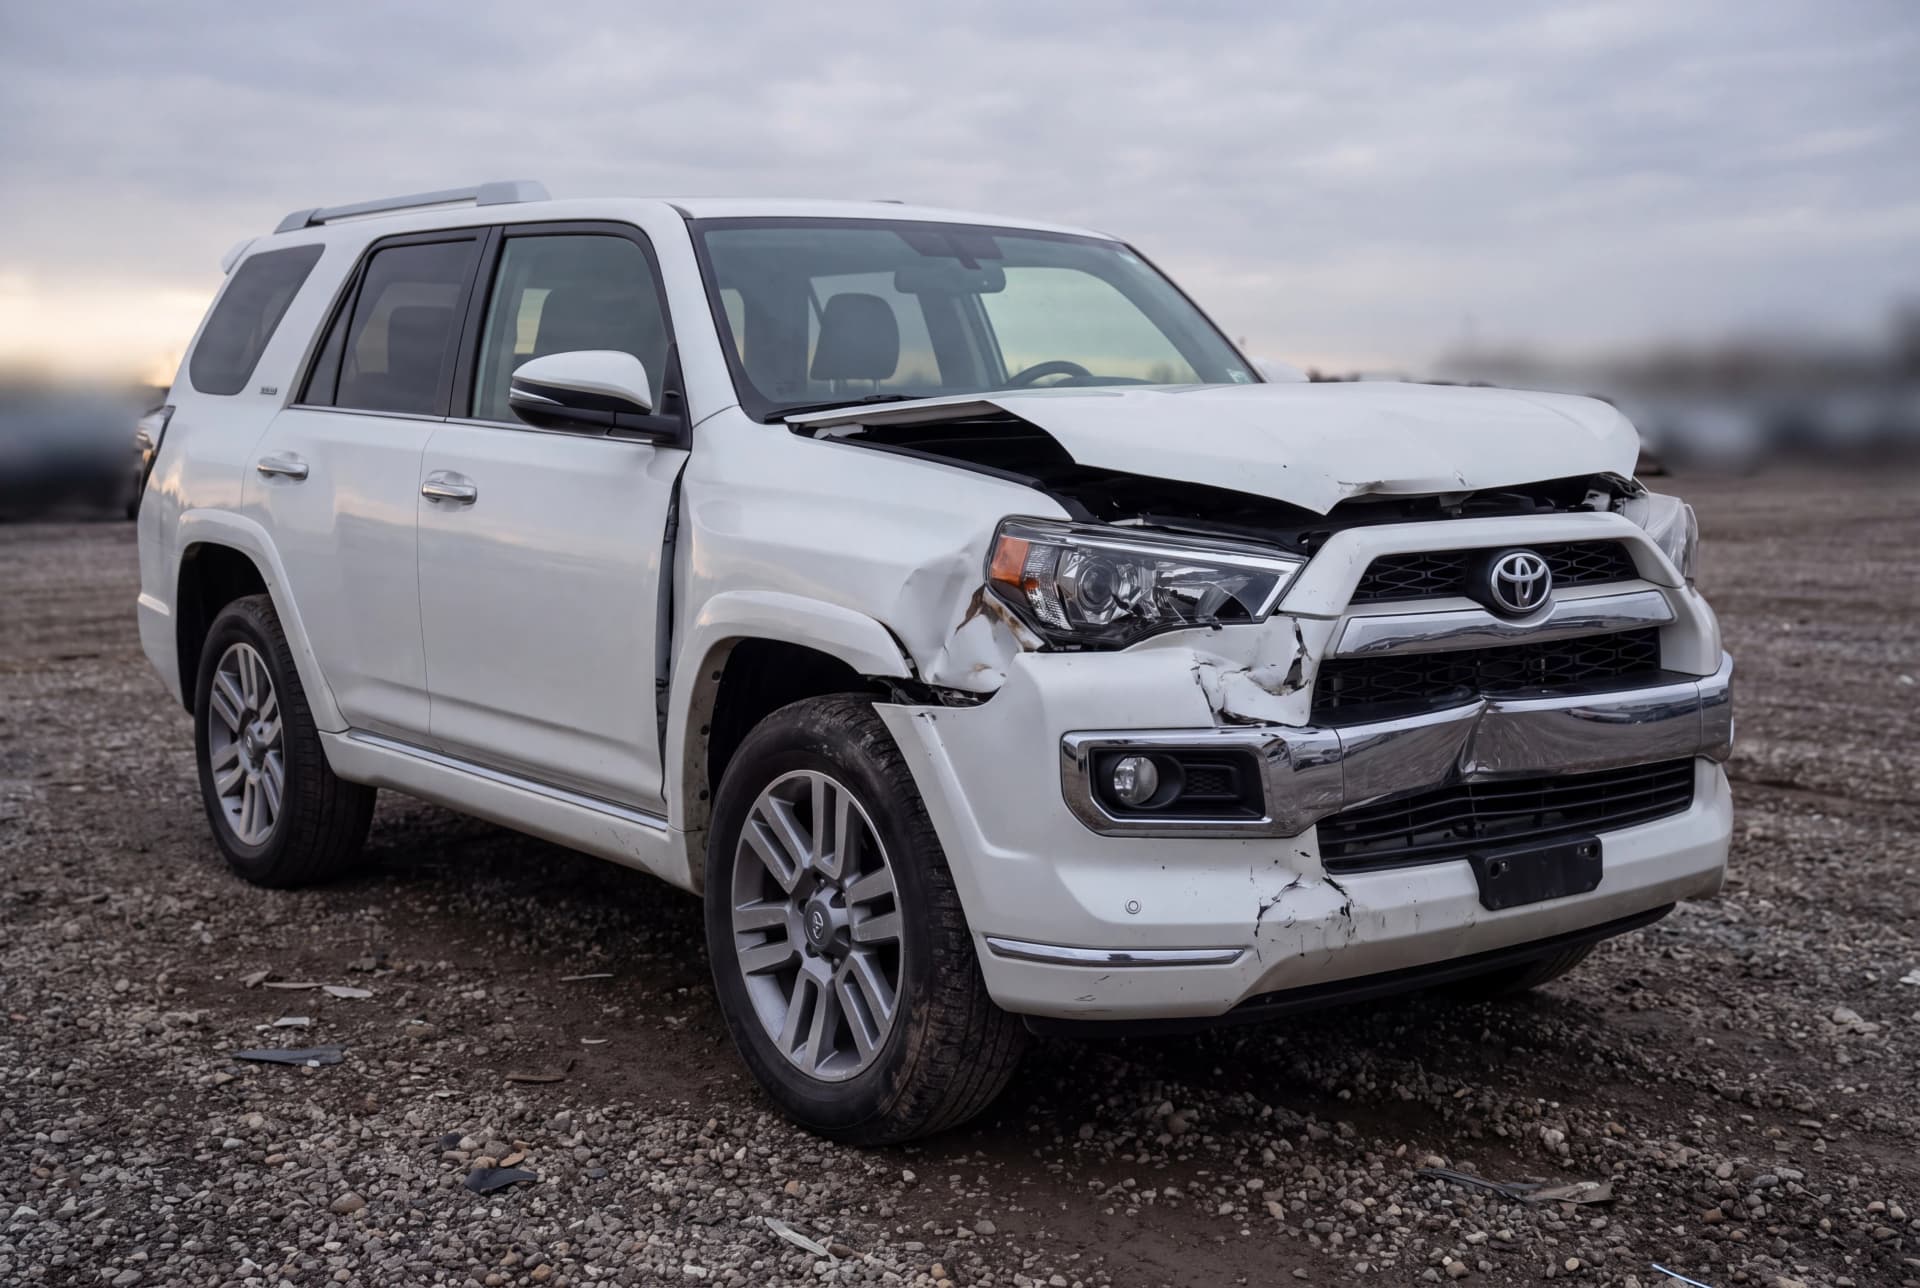
Another successful outcome in Wyoming
When Rachel received an initial offer of $21,824 for her 2016 Toyota 4Runner in Wyoming, our research showed the insurer had come in too low. The dispute went through the policy's appraisal clause after the insurance company brought in its own appraiser. In the end, the final settlement rose to $25,250, putting an additional $3,426 back in her hands.
- Allstate’s first offer
- $21,824
- Recovered above the offer
- +$3,426
- Total settlement
- $25,250
Wyoming Total Loss Framework — § 26-13-124, § 26-15-124, § 31-2-106(v)
Wyoming's first-party total-loss framework rests on Wyo. Stat. § 26-13-124 (the Unfair Claims Settlement Practices statute, with 17 listed practices) and Wyo. Stat. § 26-15-124 (the 45-day prompt-payment rule and attorney-fee remedy). Section 26-13-124 does not provide a private cause of action (Viking Ins. Co. of Wisconsin v. Baize, 10th Cir. 2018), but the Wyoming Supreme Court recognized first-party bad faith as an independent tort in McCullough v. Golden Rule, 789 P.2d 855 (Wyo. 1990), measured by "the objective standard whether the validity of the denied claim was not fairly debatable"; Herrig v. Herrig (Wyo. 1992) describes it as knowingly or recklessly denying a first-party claim without a reasonable basis. Under § 26-15-124(c), when an insurer's refusal to pay "the full amount of a loss covered by the policy" is "unreasonable or without cause," a court rendering judgment for the claimant may award a reasonable attorney's fee and interest at 10% per year. Under § 31-2-106(a)(v), a salvage vehicle is one declared a total loss by the insurance company or, when no insurance company is involved in the settlement, one whose repair cost exceeds 75% of its actual retail cash value.
Wyoming Department of Insurance
If you believe your insurer is acting in bad faith, you can file a complaint with Wyoming Department of Insurance — Consumer Affairs at 307-777-7402 — doi.wyo.gov ↗.
How SecondAppraisal helps Wyoming policyholders
- Free appraisal consultation — confirm your offer is below fair market value before you commit.
- VIN-decoded option audit so every factory feature is credited.
- Accurate and appropriate comparable vehicle research.
- Line-by-line audit of the insurer's adjustments.
- Once you invoke the appraisal clause, we carry out the appraisal process.
Frequently asked questions
What is the total-loss threshold in Wyoming?▼
Can I invoke the appraisal clause in a third-party insurance carrier / at-fault insurance carrier claim in Wyoming?▼
What does SecondAppraisal cost in Wyoming?▼
How long does a Wyoming total-loss appraisal take?▼
Ready to push back on a low Wyoming total-loss offer?
Start your free appraisal consultation in 5 minutes. Our clients average $3,648 in additional settlement value — and we guarantee at least $1,000 more or you pay nothing.
Get My Free Appraisal Consultation