Maine Total Loss Appraisal

Get the fair value you deserve for your totaled vehicle in Maine

In Maine, your auto policy's appraisal clause gives you the right to appoint SecondAppraisal as your independent appraiser in a total-loss dispute.

Maine Total-Loss Threshold
Total Loss Formula (TLF)
Appraisal Clause
Available in most policies
Fair Claims Settlement Practices
24-A M.R.S. §§ 2164-D, 2436, 2436-A; 24-A M.R.S. § 2910-B
Appraiser Licensing
Review appointment requirements
Official source
legislature.maine.gov ↗

How SecondAppraisal helps

  • •Free appraisal consultation — we review your offer before you commit.
  • •At least $1,000 more, or your fee is waived. This applies once we accept your consultation and serve as your appraiser. The starting point is your insurer's offer on the day we accept. If the appraisal award, or a higher offer your insurer makes instead, is less than $1,000 above it, we waive our $495 Appointed Appraiser Service fee. If an umpire is needed, the umpire's fee is separate.
  • •Average increase: $3,648 over the insurer's first offer (264 finished consultations that settled at or above the first offer, through Sep 25, 2026, before our fee).

How a total loss works in Maine

Insurance carriers in Maine use the Total Loss Formula (TLF) method. When the cost of repair plus the salvage value of your damaged vehicle equals or exceeds its pre-loss actual cash value (ACV), your insurer will declare your vehicle a total loss rather than authorize the repair. From that point, the dispute shifts from "will they fix it?" to "how much will they pay?"

Your appraisal-clause rights in Maine

Most US auto policies — including those issued in Maine — contain an appraisal clause that lets either you or the insurer demand a binding independent appraisal when you disagree on value. When invoked, you and the insurer each select a competent independent appraiser, and typically those two appraisers will agree to a new actual cash value. In the event those two appraisers are unable to agree on a value, the two appraisers can select an Umpire to break ties. Typically, you will split the cost of the third appraiser/umpire with the insurance carrier 50/50. In the event that the two appraisers are unable to agree on an umpire, the insured or the insurance carrier can petition a court with jurisdiction to select one. This rarely happens, but the chance isn't zero. The resulting valuation from any two appraisers and/or the umpire is binding.
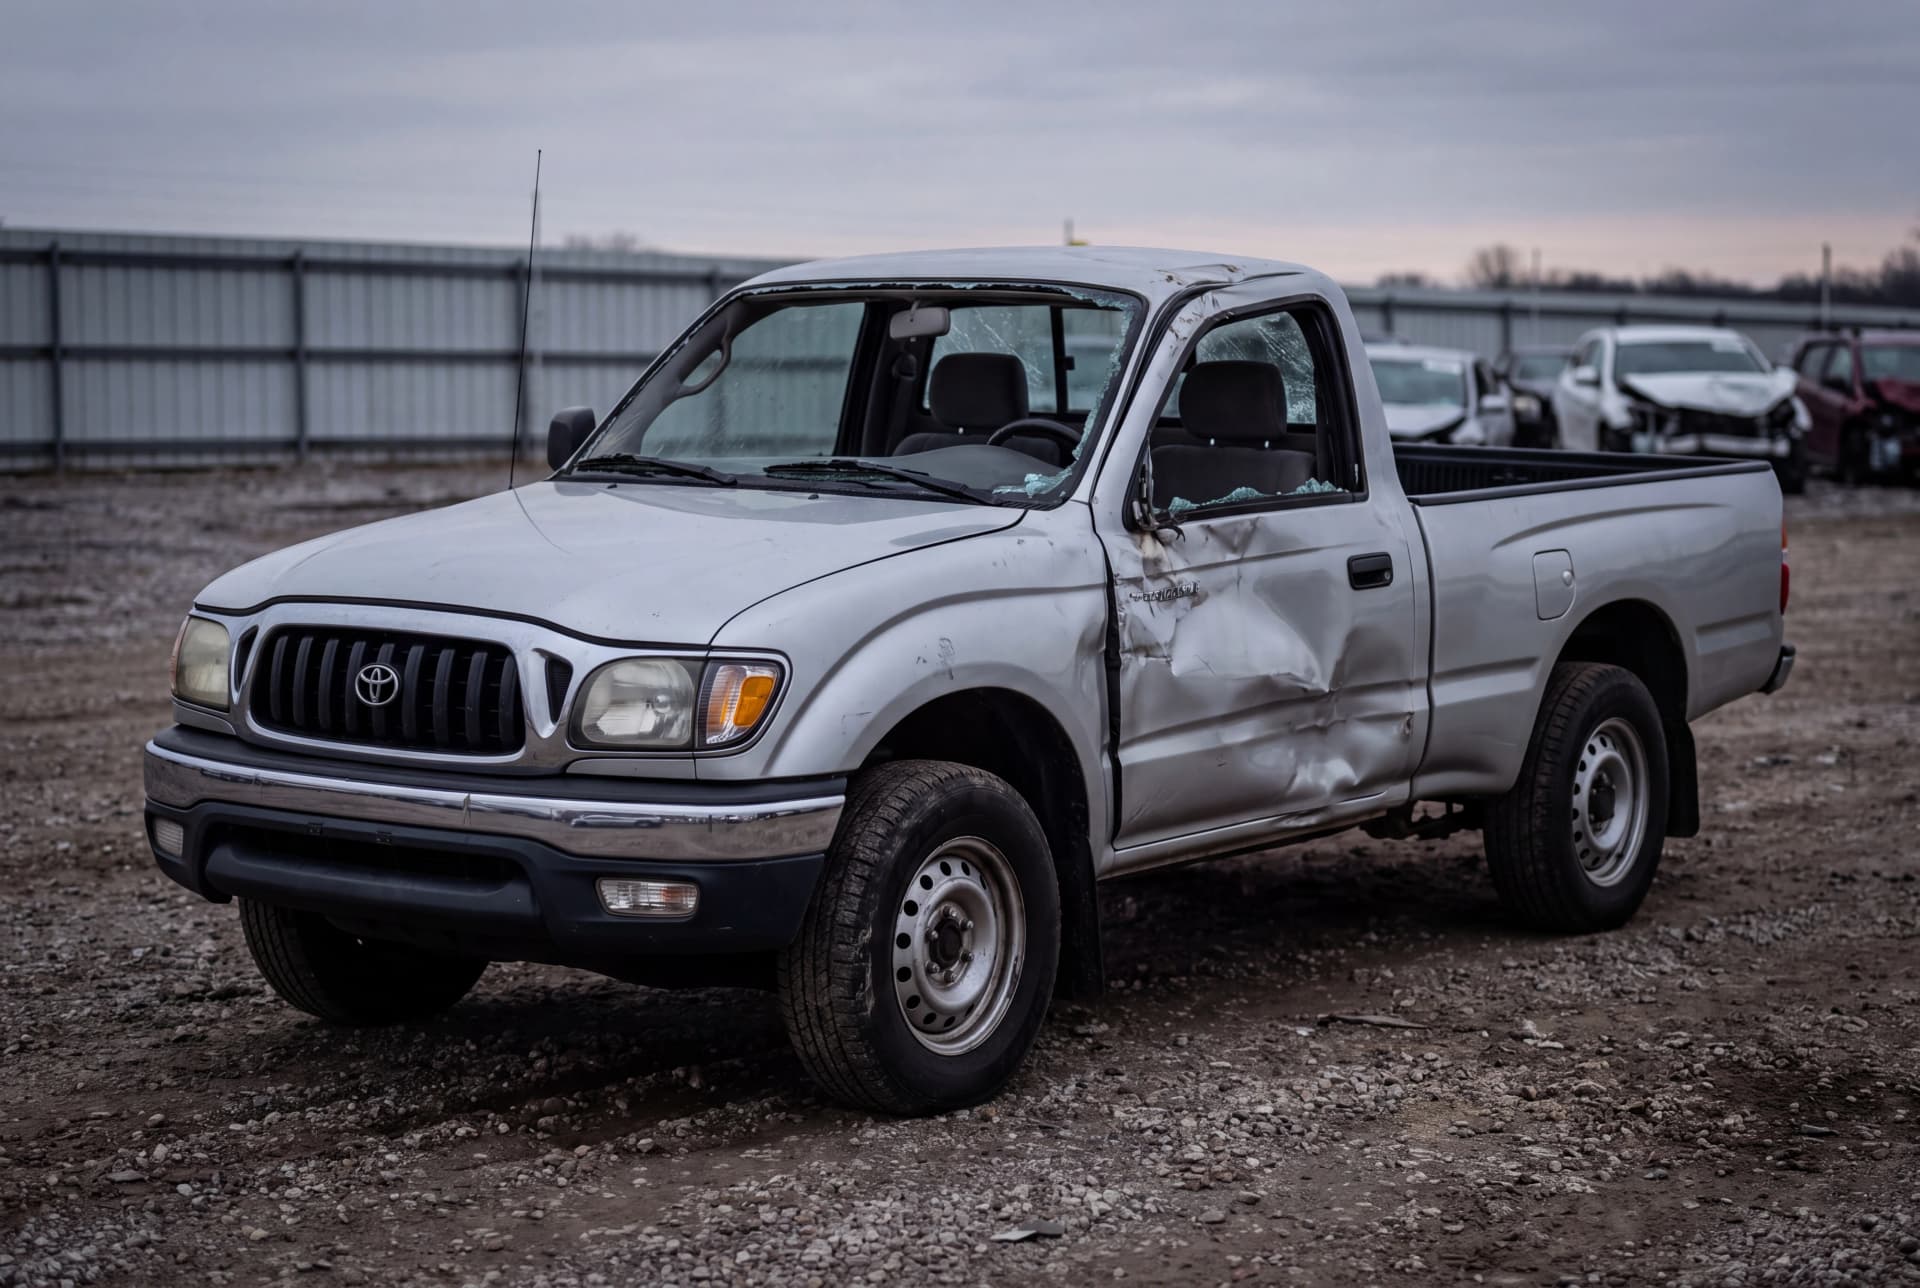
A totaled Silver 2003 Toyota Tacoma Base after a passenger-side collision

Another successful outcome in Maine

“Amazing experience. We were being majorly lowballed by my insurance company for my ‘03 Tacoma and Jonathan helped us raise the actual cash value by over $5k. He was super transparent and nice to work with, and overall brought a silver lining to an extremely stressful situation.”

— Paige W., Maine

When Adam was offered $7,348 by his insurer for his 2003 Toyota Tacoma in Maine, our research showed that initial amount was far too low. After the dispute entered the policy appraisal clause, the final settlement rose to $12,200. That secured him $4,852 above the original offer.

AAA’s first offer
$7,348
Recovered above the offer
+$4,852
Total settlement
$12,200

One customer's result, before our fee.

Total-loss help in Maine

Maine Total Loss Framework — 24-A M.R.S. §§ 2164-D, 2436, 2436-A + Marquis v. Farm Family

Maine is one of a small number of states with an explicit UCSPA private right of action codified directly in the Insurance Code. 24-A M.R.S. § 2436-A allows an insured injured by any of the five practices it lists (among them failing, without just cause, to settle a claim once liability has become reasonably clear) to recover damages, costs and disbursements, reasonable attorney's fees, and interest on damages at 1.5% per month (effectively 18% per annum). 24-A M.R.S. § 2436 sets late-payment timing rules. § 2164-D defines unfair claim settlement practices but expressly disclaims a private cause of action under that section itself (§ 2164-D(8)) — the private remedy lives in § 2436-A. Maine does NOT recognize a separate common-law first-party bad-faith tort — the Maine Supreme Judicial Court held in Marquis v. Farm Family (Me. 1993) that §§ 2436 and 2436-A were the legislature's chosen remedy. Maine does not appear to codify a specific percentage-of-fair-market-value salvage threshold by statute; industry practice generally follows the TLF (Total Loss Formula).

Maine regulates first-party automobile total losses through statutory authorities in Title 24-A: the Unfair Claim Settlement Practices Act at 24-A M.R.S. § 2164-D (regulatory, no private right of action under the section itself per § 2164-D(8)), the late-payment statute at 24-A M.R.S. § 2436, and the private-right-of-action statute at 24-A M.R.S. § 2436-A. Maine does not recognize a common-law first-party bad-faith tort — the Maine Supreme Judicial Court declined to do so in Marquis v. Farm Family Mutual Insurance Co., 628 A.2d 644 (Me. 1993), reasoning that the legislature had spoken through §§ 2436 and 2436-A. 24-A M.R.S. § 2164-D — Unfair Claim Settlement Practices. The statute defines acts that constitute unfair claim settlement practices, including: misrepresenting pertinent facts or insurance policy provisions; failing to acknowledge with reasonable promptness pertinent written communications about claims; failing to adopt and implement reasonable standards for the prompt investigation of claims; refusing to pay claims without conducting a reasonable investigation; failing to affirm or deny coverage of claims within a reasonable time; failing, without just cause and with such frequency as to indicate a general business practice, to deal with insureds in good faith to resolve claims; and compelling insureds to institute litigation to recover amounts due. Section 2164-D(8) provides that "This section may not be construed to create or imply a private cause of action for violation of this section"; the private remedy lives in § 2436-A. 24-A M.R.S. § 2436-A — Unfair Claim Settlement Practices Private Right of Action. Maine is one of a small number of states with an explicit private right of action under the UCSPA. The statute lets a person injured by any of five listed actions of that person's own insurer recover damages, costs and disbursements, reasonable attorney's fees, and interest on damages at 1.5% per month: knowingly misrepresenting pertinent facts or policy provisions relating to coverage; failing to acknowledge and review claims within a reasonable time after written notice; threatening to appeal an arbitration award to force a smaller settlement; failing to affirm or deny coverage within a reasonable time after completing the investigation; and, without just cause, failing to effectuate prompt, fair and equitable settlement of claims in which liability has become reasonably clear. Under § 2436-A(2), an insurer acts without just cause if it refuses to settle without a reasonable basis to contest liability, the amount of damages or the extent of injuries. The 1.5%-per-month interest provision (often referenced as an 18%-per-annum effective rate) is unusually robust as a statutory floor for time-value-of-money exposure. 24-A M.R.S. § 2436 — Late Payment of Claims. Maine's late-payment statute sets timing rules for the payment or denial of claims; the precise statutory deadline varies by claim type (for example, the statute references a 60-day window for certain fire-insurance contexts). Readers should consult the current text of § 2436 for the operative deadline on a given claim; under § 2436(3), an overdue undisputed claim bears interest at 1 1/2% per month after the due date. Maine total-loss valuation methodology. Maine does not appear to have a comprehensive total-loss valuation regulation analogous to Massachusetts 211 CMR 133 or Maryland COMAR 31.15.12. Maine total-loss claims are governed by the policy's terms and by general UCSPA principles under § 2164-D, with statutory comparable-vehicle restrictions in 24-A M.R.S. § 2910-B (enacted in 2021) limiting comparables in certain contexts. Marquis v. Farm Family Mutual Insurance Co., 628 A.2d 644 (Me. 1993). The Maine Supreme Judicial Court declined to recognize a common-law first-party bad-faith tort, holding that the legislature had spoken through §§ 2436 and 2436-A and that creating a parallel tort would be inconsistent with the legislative scheme. § 2436-A remains the primary statutory lever, with its damages + costs + attorney's fees + 1.5%/month interest structure. Maine salvage titling is governed by the current Title 29-A salvage provisions; Maine does not appear to codify a specific percentage-of-fair-market-value threshold by statute (29-A M.R.S. § 1855 has been repealed). Industry practice in Maine is commonly described as following the Total Loss Formula, an industry methodology rather than a statutory percentage.
As of May 21, 2026
Excerpt — full statute at official source.

Maine Department of Insurance

If you believe your insurer is acting in bad faith, you can file a complaint with Maine Bureau of Insurance — Consumer Health Care Division at 800-300-5000 — maine.gov ↗.

How SecondAppraisal helps Maine policyholders

  1. Free appraisal consultation — confirm your offer is below fair market value before you commit.
  2. VIN-decoded option audit so every factory feature is credited.
  3. Accurate and appropriate comparable vehicle research.
  4. Line-by-line audit of the insurer's adjustments.
  5. Once you invoke the appraisal clause, we carry out the appraisal process.

Frequently asked questions

What is the total-loss threshold in Maine?▼
Maine uses the Total Loss Formula (TLF) method, not a fixed percent. Your insurer is required to declare your vehicle a total loss when the cost of repair plus the salvage value of the damaged vehicle equals or exceeds the pre-loss actual cash value (ACV).
Can I invoke the appraisal clause in a third-party insurance carrier / at-fault insurance carrier claim in Maine?▼
Generally no — the appraisal clause is part of YOUR policy, not the at-fault driver's. If you are stuck with a third-party insurance carrier that refuses to negotiate, you can often switch to a first-party claim under your own policy and let your insurer pursue subrogation.
What does SecondAppraisal cost in Maine?▼
Your appraisal consultation is free. The Appointed Appraiser Service is $495. It includes the Appraisal Research, our appointment as your appraiser under your insurance policy's appraisal clause, determining the amount of loss with your insurer's appraiser, and the appraisal award letter. At least $1,000 more, or your fee is waived. This applies once we accept your consultation and serve as your appraiser. The starting point is your insurer's offer on the day we accept. If the appraisal award, or a higher offer your insurer makes instead, is less than $1,000 above it, we waive our $495 Appointed Appraiser Service fee. If an umpire is needed, the umpire's fee is separate. There is no upfront payment: we pre-authorize your card only after we accept your consultation. Our results: $3,648 more than the insurer's first offer, on average, before our fee. From 264 finished consultations that settled at or above the insurer's first offer, through September 25, 2026; past results, not a promise.
How long does a Maine total-loss appraisal take?▼
How long the appraisal takes depends on your insurer's appraiser and, if one is needed, the umpire.

Ready to push back on a low Maine total-loss offer?

Start your free appraisal consultation in 5 minutes. At least $1,000 more than your insurer's offer, or your $495 fee is waived, once we accept your consultation. Our results: $3,648 more than the insurer's first offer, on average, before our fee. From 264 finished consultations that settled at or above the insurer's first offer, through September 25, 2026; past results, not a promise.

Get My Free Appraisal Consultation