Get the fair value you deserve for your totaled vehicle in Ohio
In Ohio, your auto policy's appraisal clause gives you the right to appoint SecondAppraisal as your independent appraiser in a total-loss dispute.
Key takeaway
Ohio Adm. Code 3901-1-54(H)(7) requires an insurer that elects to offer a cash settlement for an automobile total loss to base the offer on the actual cost to purchase a comparable automobile, less any applicable deductible and any betterment deduction under paragraph (H)(2), and lists the sources the settlement value may be derived from. Under (H)(7)(f), an insurer that settles a total loss on a cash settlement basis must maintain in the claim file the documentation used to determine the loss and provide it to the first-party claimant on request. Paragraph (A) states that nothing in the rule shall be construed to create or imply a private cause of action for its violation, and under paragraph (K) the superintendent may, pursuant to R.C. 3901.22 and a consent agreement with the insurer, recover the cost of an investigation, a penalty, or both from the insurer.
How SecondAppraisal helps
- •Free appraisal consultation — we review your offer before you commit.
- •At least $1,000 more, or your fee is waived. This applies once we accept your consultation and serve as your appraiser. The starting point is your insurer's offer on the day we accept. If the appraisal award, or a higher offer your insurer makes instead, is less than $1,000 above it, we waive our $495 Appointed Appraiser Service fee. If an umpire is needed, the umpire's fee is separate.
- •Average increase: $3,648 over the insurer's first offer (264 finished consultations that settled at or above the first offer, through Sep 25, 2026, before our fee).
How a total loss works in Ohio
Insurance carriers in Ohio use the Total Loss Formula (TLF) method. When the cost of repair plus the salvage value of your damaged vehicle equals or exceeds its pre-loss actual cash value (ACV), your insurer will declare your vehicle a total loss rather than authorize the repair. From that point, the dispute shifts from "will they fix it?" to "how much will they pay?"
Your appraisal-clause rights in Ohio
Most US auto policies — including those issued in Ohio — contain an appraisal clause that lets either you or the insurer demand a binding independent appraisal when you disagree on value. When invoked, you and the insurer each select a competent independent appraiser, and typically those two appraisers will agree to a new actual cash value. In the event those two appraisers are unable to agree on a value, the two appraisers can select an Umpire to break ties. Typically, you will split the cost of the third appraiser/umpire with the insurance carrier 50/50. In the event that the two appraisers are unable to agree on an umpire, the insured or the insurance carrier can petition a court with jurisdiction to select one. This rarely happens, but the chance isn't zero. The resulting valuation from any two appraisers and/or the umpire is binding.
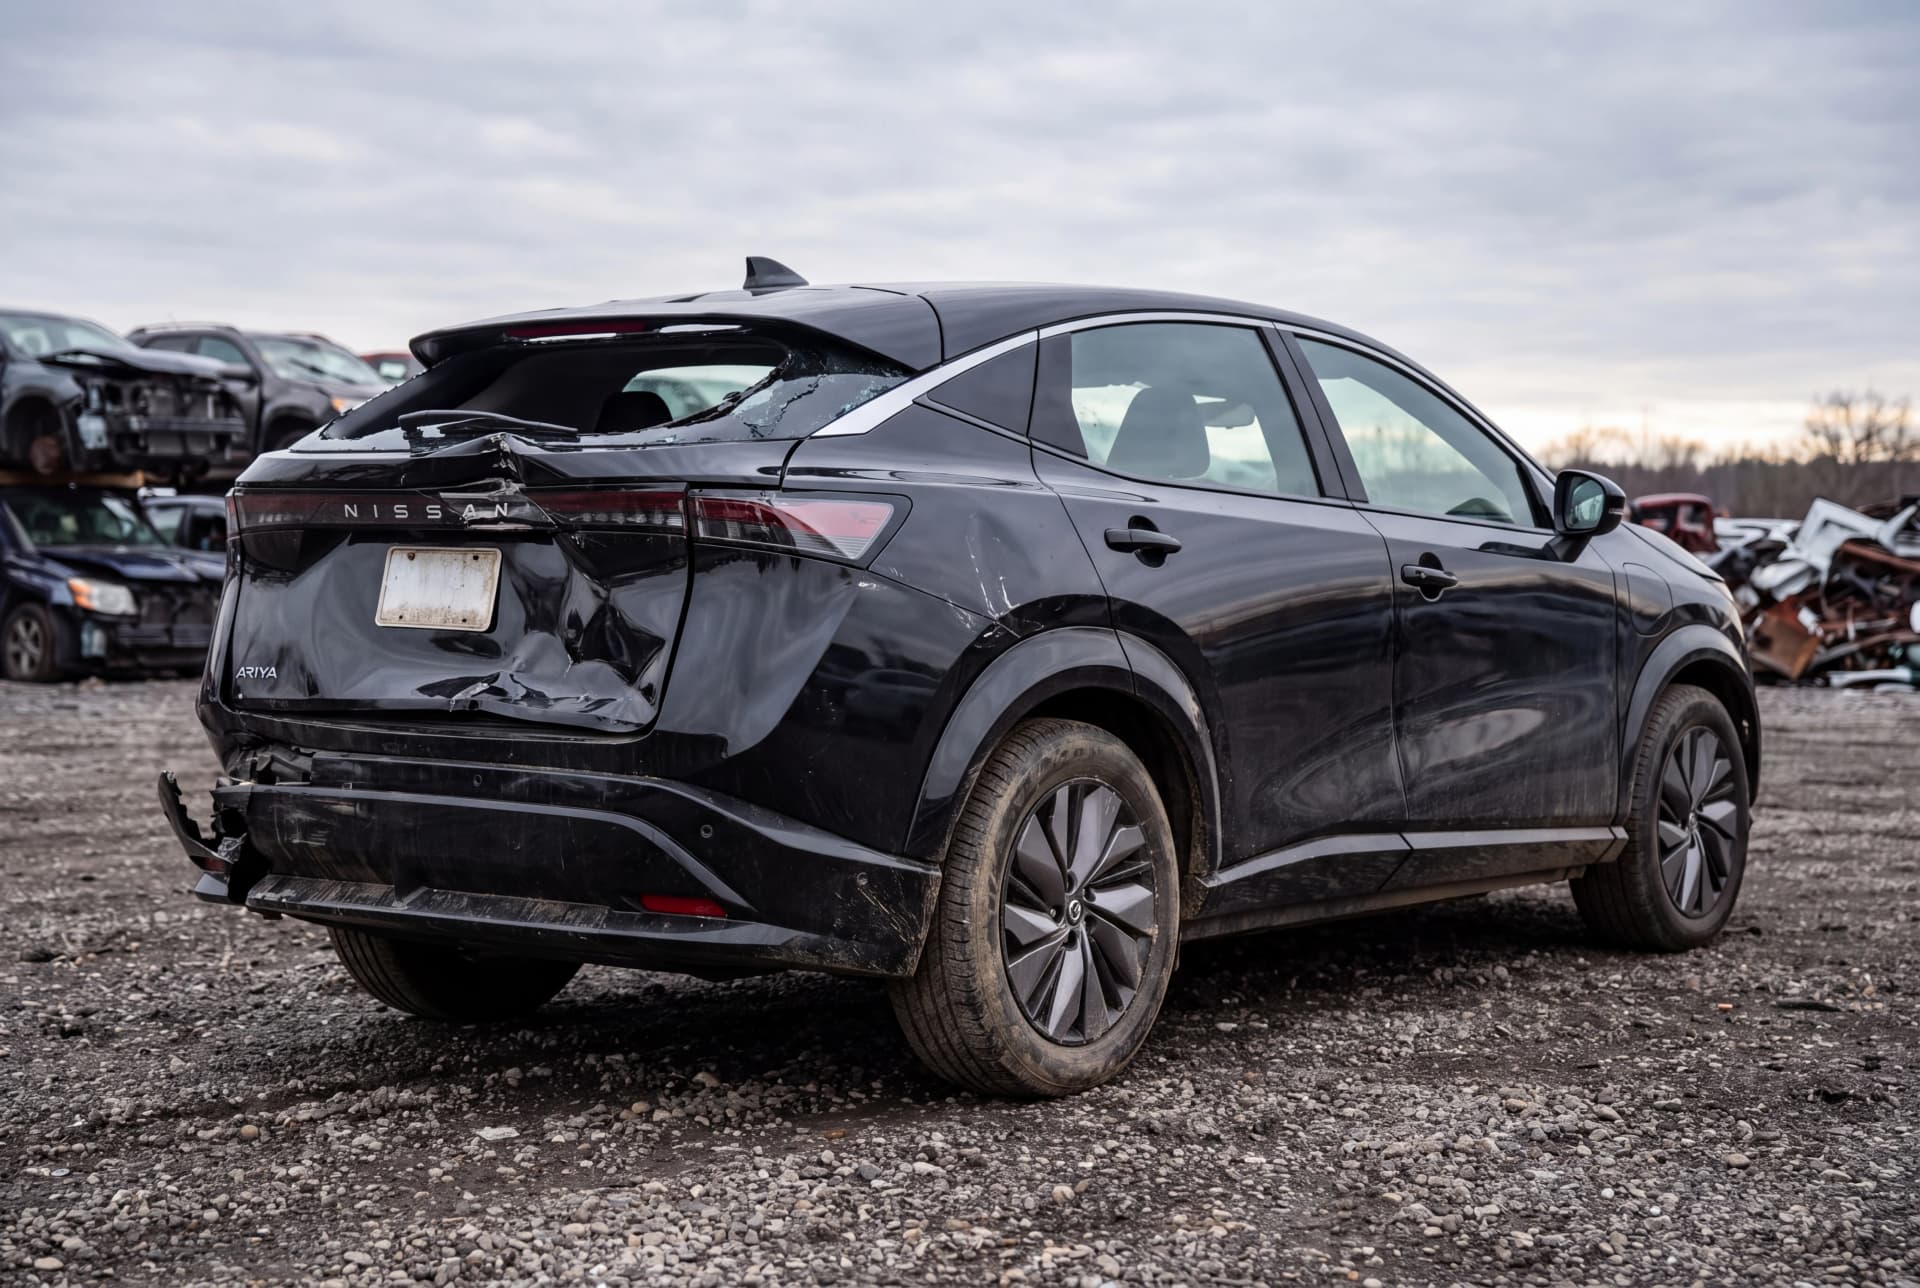
Another successful outcome in Ohio
“SecondAppraisal is great - they got me an extra $6,122 above what those jerks at my insurance company were offering after my 2023 vehicle was totaled! Jonathon was extremely communicative and kept me informed at every step. The website was easy to use and clearly documented every step of the process.”
When his insurer first offered $20,095 for his 2023 Nissan Ariya, Ben reached out to us to see what was fair. Our research showed the vehicle was actually worth $26,217, so the claim proceeded through the policy appraisal clause. The final settlement came in at $26,217, securing Ben $6,122 more than the initial offer.
- Allstate’s first offer
- $20,095
- Recovered above the offer
- +$6,122
- Total settlement
- $26,217
One customer's result, before our fee.
Total-loss help in OhioOhio Total Loss Framework — O.R.C. §§ 3901.20–3901.21 + Ohio Adm. Code 3901-1-54(H)
Ohio regulates auto total losses through O.R.C. §§ 3901.20–3901.21 (unfair claim practices) and Ohio Adm. Code 3901-1-54(H). Subsection (H)(7) lists the sources a cash settlement's value may be derived from: the average cost of two or more comparable automobiles available in the local market area within the last ninety days, then in proximate areas, then the average of two or more licensed-dealer quotations, or a generally recognized used motor vehicle industry source (an electronic database, or a guidebook with documented adjustments). Subsection (H)(7)(f) requires the insurer to reimburse sales tax on a replacement bought within 30 days, to keep the valuation documentation in the claim file and provide it on request, and to notify the claimant of any rights to renegotiate the settlement if a comparable vehicle is not available for purchase within thirty-five days. The rule explicitly states it does not create a private right of action — leverage runs through Ohio Department of Insurance complaints and the contractual appraisal clause.
Common things to look for in Ohio
Recognize these scenarios in your offer letter or comparable report — and what we do about them.
Out-of-area comparables when local-market comparables exist
Ohio Adm. Code 3901-1-54(H)(7)(a)–(c) starts with comparables available in the local market area within the last ninety days, turns to proximate areas only when none are available locally, and to dealer quotations only when comparables are not available under (a) or (b). Demand the insurer document why local-market comparables within the ninety-day window were unavailable before reaching outside.
Refusing to provide the claim-file documentation
Ohio Adm. Code 3901-1-54(H)(7)(f) requires an insurer that settles a total loss on a cash settlement basis to maintain in the claim file the documentation used to determine the loss and to provide that information to the first-party claimant on request. A refusal to produce it can be taken to the Ohio Department of Insurance through a consumer complaint.
Ohio Department of Insurance
If you believe your insurer is acting in bad faith, you can file a complaint with Ohio Department of Insurance — Consumer Services at 800-686-1526 — gateway.insurance.ohio.gov ↗.
How SecondAppraisal helps Ohio policyholders
- Free appraisal consultation — confirm your offer is below fair market value before you commit.
- VIN-decoded option audit so every factory feature is credited.
- Accurate and appropriate comparable vehicle research.
- Line-by-line audit of the insurer's adjustments.
- Once you invoke the appraisal clause, we carry out the appraisal process.
Total-loss help in major Ohio cities
City-specific total-loss guides with local risk factors and your appraisal-clause rights:
Frequently asked questions
What is the total-loss threshold in Ohio?▼
Can I invoke the appraisal clause in a third-party insurance carrier / at-fault insurance carrier claim in Ohio?▼
What does SecondAppraisal cost in Ohio?▼
How long does an Ohio total-loss appraisal take?▼
Ready to push back on a low Ohio total-loss offer?
Start your free appraisal consultation in 5 minutes. At least $1,000 more than your insurer's offer, or your $495 fee is waived, once we accept your consultation. Our results: $3,648 more than the insurer's first offer, on average, before our fee. From 264 finished consultations that settled at or above the insurer's first offer, through September 25, 2026; past results, not a promise.
Get My Free Appraisal Consultation