Get the fair value you deserve for your totaled vehicle in Oklahoma
In Oklahoma, your auto policy's appraisal clause gives you the right to appoint SecondAppraisal as your independent appraiser in a total-loss dispute.
Key takeaway
Where a policy settles first-party total losses on actual cash value or like-kind replacement, 36 O.S. § 1250.8(A) provides two methods: a specific comparable replacement vehicle available to the insured at no cost beyond the deductible, or cash based on the actual cost, less any deductible, of a comparable vehicle with taxes, license and transfer fees. That cost may be determined from local comparables available within the prior 90 days, one of two or more quotations from qualified local dealers when none is available locally, or the latest NADA Official Used Car Guide or another nationally recognized guidebook's monthly edition. Section 1250.8(B) requires a deviation from those methods to be documented with details of the vehicle's condition, and any deductions from the cost, including deduction for salvage, to be "measurable, discernible, itemized and specified as to dollar amount." Christian v. American Home Assurance Co., 1977 OK 141, ¶¶25–26, recognized a tort claim, with consequential and, in a proper case, punitive damages, for an insurer's breach of its implied duty to deal fairly and act in good faith with its insured, but only on a clear showing that the insurer unreasonably, and in bad faith, withholds payment of the claim of its insured. Under 36 O.S. § 3629(B), costs and attorney fees are allowable to the prevailing party: the insurer if the judgment does not exceed its written settlement offer, otherwise the insured, whose verdict carries 15% annual interest from the date the loss was payable until the verdict. Section 3629(B) adds: "This provision shall not apply to uninsured motorist coverage."
How SecondAppraisal helps
- •Free appraisal consultation — we review your offer before you commit.
- •At least $1,000 more, or your fee is waived. This applies once we accept your consultation and serve as your appraiser. The starting point is your insurer's offer on the day we accept. If the appraisal award, or a higher offer your insurer makes instead, is less than $1,000 above it, we waive our $495 Appointed Appraiser Service fee. If an umpire is needed, the umpire's fee is separate.
- •Average increase: $3,648 over the insurer's first offer (264 finished consultations that settled at or above the first offer, through Sep 25, 2026, before our fee).
How a total loss works in Oklahoma
Insurance carriers in Oklahoma use the Total Loss Threshold (TLT) method. When the cost to repair your vehicle reaches 60% of its pre-loss actual cash value (ACV), your insurer will declare your vehicle a total loss rather than authorize the repair. From that point, the dispute shifts from "will they fix it?" to "how much will they pay?"
Your appraisal-clause rights in Oklahoma
Most US auto policies — including those issued in Oklahoma — contain an appraisal clause that lets either you or the insurer demand a binding independent appraisal when you disagree on value. When invoked, you and the insurer each select a competent independent appraiser, and typically those two appraisers will agree to a new actual cash value. In the event those two appraisers are unable to agree on a value, the two appraisers can select an Umpire to break ties. Typically, you will split the cost of the third appraiser/umpire with the insurance carrier 50/50. In the event that the two appraisers are unable to agree on an umpire, the insured or the insurance carrier can petition a court with jurisdiction to select one. This rarely happens, but the chance isn't zero. The resulting valuation from any two appraisers and/or the umpire is binding.
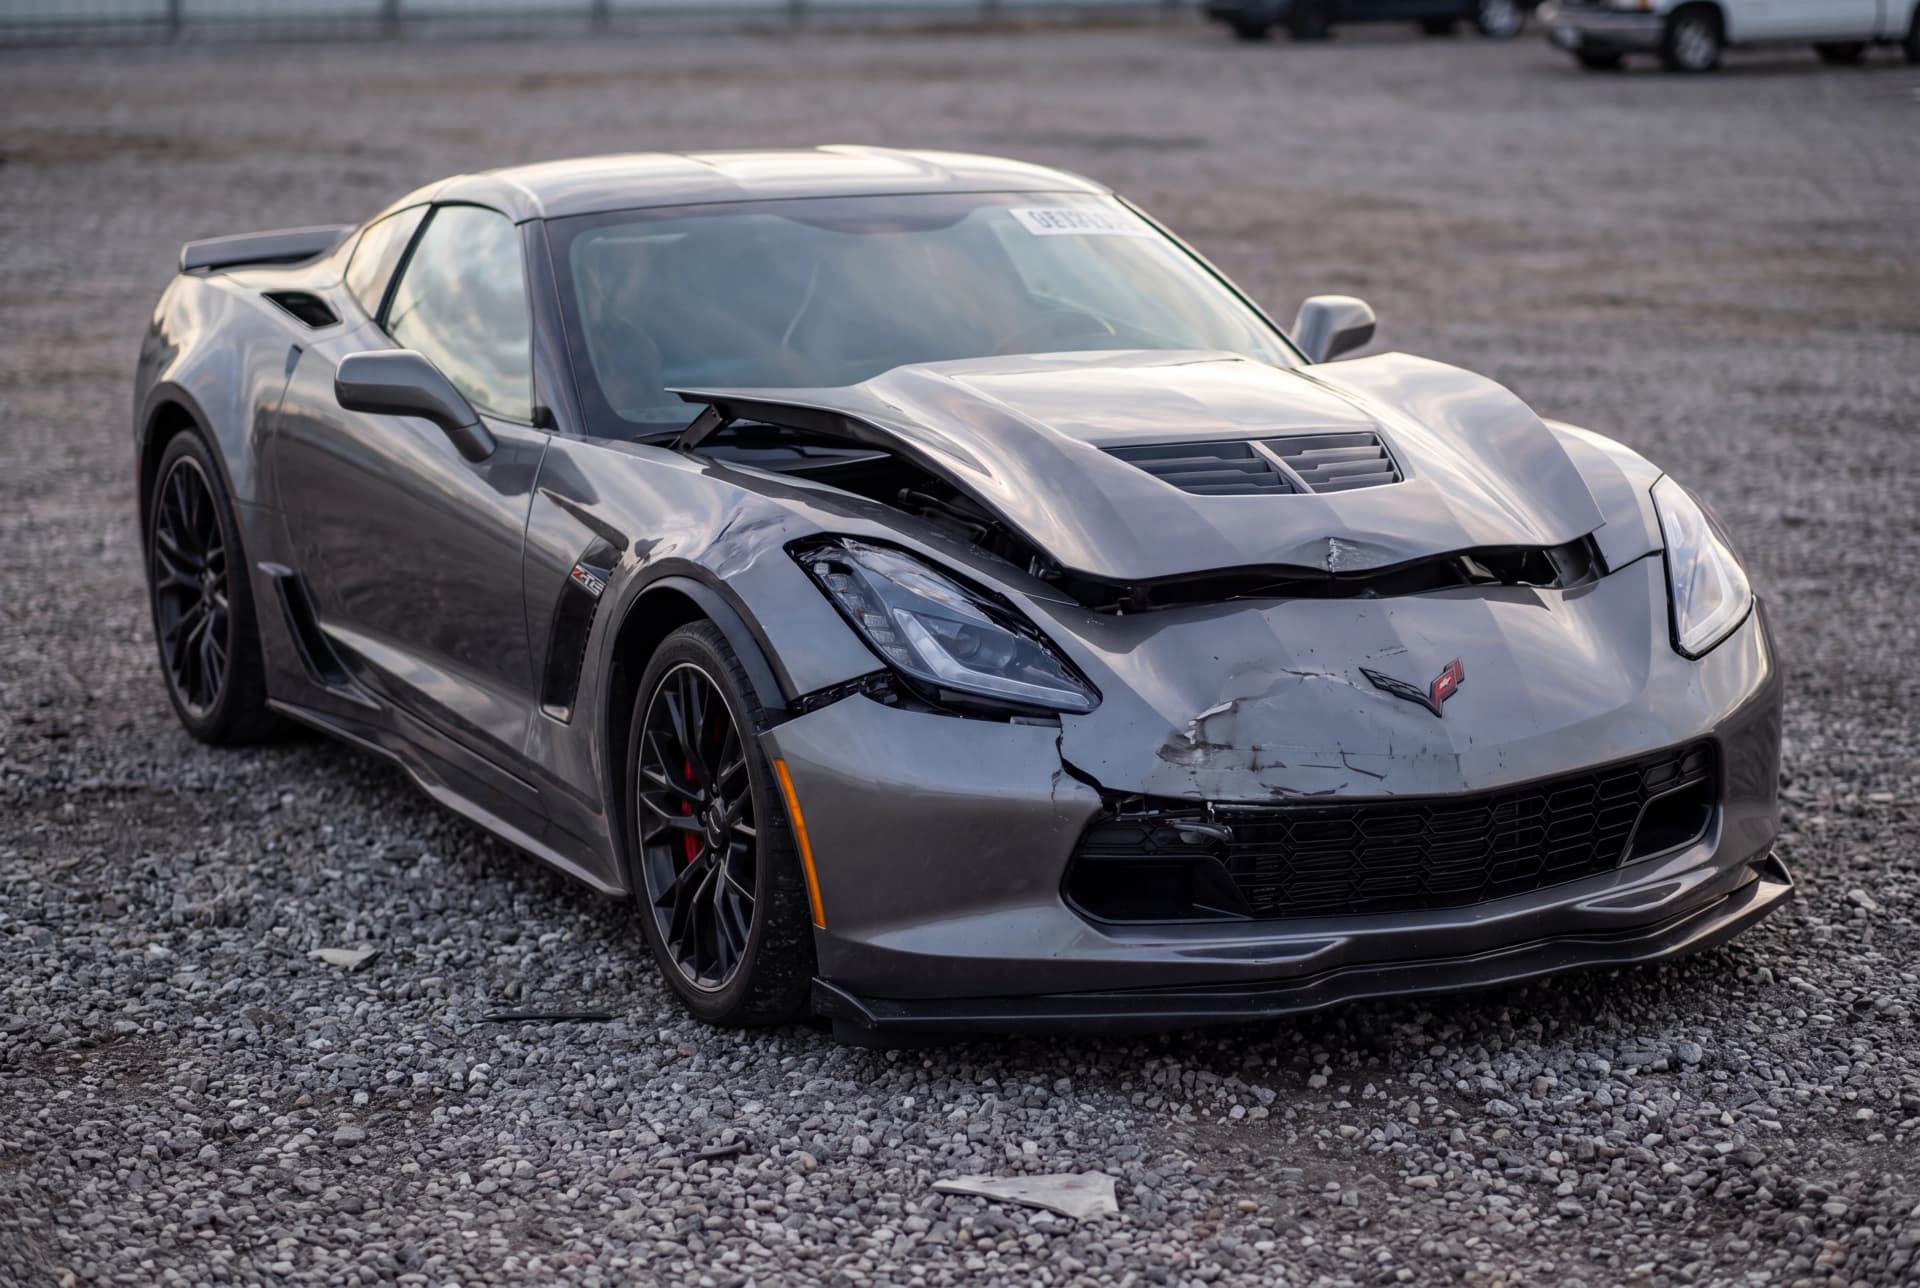
Another successful outcome in Oklahoma
“Easy and painless. Jonathon took great care of me. Insurance company originally offered me $47,566 for my 2015 Corvette Z06 m7, total loss. Jonathon did the appraisal and got me $60,130 plus taxes and fees. I feel like that was a fair settlement as my car had 83k miles.”
Sean received an initial offer of $47,566 from his insurance company for his 2015 Chevrolet Corvette in Oklahoma. Our research showed that the initial offer was too low, so the dispute went through the policy appraisal clause after the insurer brought in an appraiser. The final settlement came to $60,130, which recovered $12,564 above the original amount.
- Encompass’ first offer
- $47,566
- Recovered above the offer
- +$12,564
- Total settlement
- $60,130
One customer's result, before our fee.
Total-loss help in OklahomaYour Oklahoma rights at a glance
Settlement methodology under 36 O.S. § 1250.8
The insurer must either (a) offer a specific comparable replacement vehicle available to the insured with all taxes and fees paid, or (b) elect a cash settlement based on the cost of a comparable vehicle in the local market area, one of two or more quotations from qualified local dealers, or the latest NADA or other nationally recognized guidebook — with applicable taxes, license fees, and transfer fees included. A settlement that deviates from those methods must be documented, and any deductions from the cost, including deduction for salvage, must be measurable, discernible, itemized and specified as to dollar amount.
First-party bad-faith tort under Christian v. American Home + § 3629(B) statutory recovery
Christian v. American Home Assurance Co., 577 P.2d 899 (Okla. 1977), recognized first-party bad faith as a tort separate from breach of contract, available where the insurer unreasonably, and in bad faith, withholds payment of the claim. Under 36 O.S. § 3629(B), costs and attorney's fees are allowable to the prevailing party — the insured, unless the judgment does not exceed the insurer's written offer of settlement — and when the insured prevails the court adds 15%-per-annum interest from the date the loss was payable to the date of the verdict. Consequential and, in a proper case, punitive damages flow from the common-law Christian tort itself (not from § 3629(B), and not from § 1219 — which is the unrelated accident-and-health clean-claims-processing statute).
60% salvage threshold for late-model vehicles under 47 O.S. § 1105
The salvage-vehicle definition at 47 O.S. § 1105 applies to any vehicle within the last ten (10) model years where the cost of repairing the vehicle for safe operation exceeds 60% of its fair market value immediately prior to the damage. For the settlement statute, 36 O.S. § 1250.8(M) defines a total loss as repair costs plus salvage value meeting or exceeding the vehicle's pre-loss actual cash value, as provided in used automobile dealer guidebooks. That formula gives policyholders an analytical lever to challenge inflated repair-cost estimates that artificially trigger total-loss declarations on otherwise repairable vehicles.
Oklahoma Statutes § 36-1250.8 — Motor Vehicle Total Loss Claims
Oklahoma's total-loss framework is anchored in 36 O.S. § 1250.8, which requires the insurer to either offer a replacement vehicle (comparable, available to the insured, all taxes and fees paid) or elect a cash settlement, including taxes, license and transfer fees, based on the cost of a comparable vehicle in the local market area, one of two or more quotations from qualified local dealers, or the latest NADA or other nationally recognized guidebook; a settlement that deviates from those methods must be documented. Above the settlement statute sit the Oklahoma UCSPA at 36 O.S. § 1250.5 and a powerful common-law / statutory first-party bad-faith framework: Christian v. American Home Assurance Co., 577 P.2d 899 (Okla. 1977), recognized first-party bad faith as a tort, and 36 O.S. § 3629(B) allows costs and attorney's fees to the prevailing party and, when the insured prevails, adds 15%-per-annum interest from the date the loss was payable to the date of the verdict (consequential and, in a proper case, punitive damages flow from the common-law Christian tort itself). Section 1250.8(M) defines a total loss as one where the vehicle's repair costs plus its salvage value meet or exceed its pre-loss actual cash value, as provided in used automobile dealer guidebooks; separately, the salvage-vehicle definition at 47 O.S. § 1105 covers a vehicle within the last ten model years whose cost of repair for safe operation exceeds 60% of its fair market value immediately before the damage.
Common things to look for in Oklahoma
Recognize these scenarios in your offer letter or comparable report — and what we do about them.
Lump-sum or non-itemized condition deductions
36 O.S. § 1250.8(B) requires a settlement that deviates from the statute's methods to be documented, and any deductions from the cost, including deduction for salvage, to be "measurable, discernible, itemized and specified as to dollar amount." Measure generic adjustments — "typical-negotiation adjustment," round-number condition deductions, fleet-average mileage adjustments without per-mile rate documentation — against that standard, and demand the line-item dollar basis for each deduction.
Comparables drawn from outside the local market area
36 O.S. § 1250.8(A)(2)(a) is explicit on the local market area for the comparable-vehicle method. Insurers sometimes use database queries that sweep in vehicles from a different metropolitan area or out of state without market-equivalency support. Demand the underlying VINs, dealer addresses, and the geographic-area parameter.
Failure to include applicable taxes, license, and transfer fees in the cash settlement
36 O.S. § 1250.8(A)(2) is explicit that a cash settlement includes all applicable taxes, license fees and other fees incident to a transfer of evidence of ownership. Insurers sometimes quote a cash amount that excludes those costs and then refuse to add them later. Demand the inclusion in the original settlement.
Oklahoma Department of Insurance
If you believe your insurer is acting in bad faith, you can file a complaint with Oklahoma Insurance Department — Consumer Assistance at 800-522-0071 — oid.ok.gov ↗.
Relevant Oklahoma precedent
How SecondAppraisal helps Oklahoma policyholders
- Free appraisal consultation — confirm your offer is below fair market value before you commit.
- VIN-decoded option audit so every factory feature is credited.
- Accurate and appropriate comparable vehicle research.
- Line-by-line audit of the insurer's adjustments.
- Once you invoke the appraisal clause, we carry out the appraisal process.
Total-loss help in major Oklahoma cities
City-specific total-loss guides with local risk factors and your appraisal-clause rights:
Frequently asked questions
What is the total-loss threshold in Oklahoma?▼
Can I invoke the appraisal clause in a third-party insurance carrier / at-fault insurance carrier claim in Oklahoma?▼
What does SecondAppraisal cost in Oklahoma?▼
How long does an Oklahoma total-loss appraisal take?▼
Ready to push back on a low Oklahoma total-loss offer?
Start your free appraisal consultation in 5 minutes. At least $1,000 more than your insurer's offer, or your $495 fee is waived, once we accept your consultation. Our results: $3,648 more than the insurer's first offer, on average, before our fee. From 264 finished consultations that settled at or above the insurer's first offer, through September 25, 2026; past results, not a promise.
Get My Free Appraisal Consultation